Exhibit 99.2
| Q3 2026 Earnings Presentation October 20, 2026 |
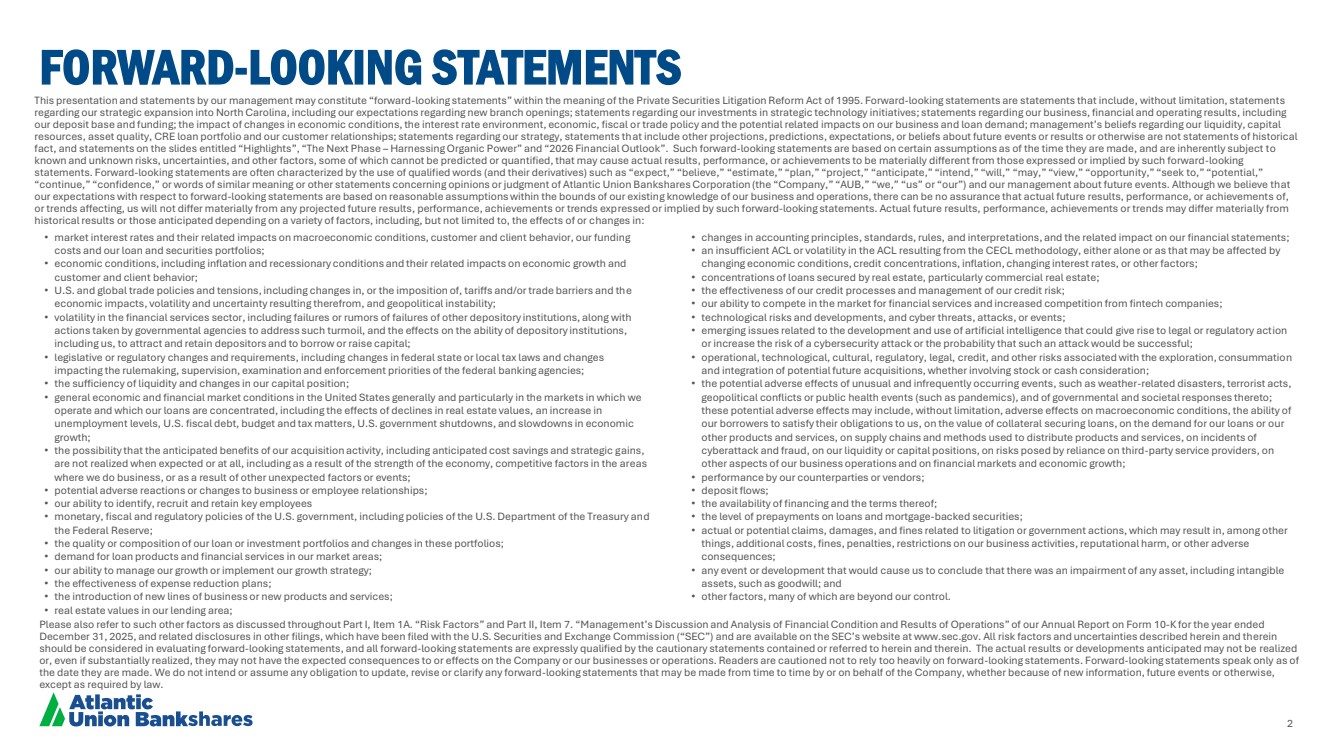
| 2 FORWARD-LOOKING STATEMENTS This presentation and statements by our management may constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements are statements that include, without limitation, statements regarding our strategic expansion into North Carolina, including our expectations regarding new branch openings; statements regarding our investments in strategic technology initiatives; statements regarding our business, financial and operating results, including our deposit base and funding; the impact of changes in economic conditions, the interest rate environment, economic, fiscal or trade policy and the potential related impacts on our business and loan demand; management’s beliefs regarding our liquidity, capital resources, asset quality, CRE loan portfolio and our customer relationships; statements regarding our strategy, statements that include other projections, predictions, expectations, or beliefs about future events or results or otherwise are not statements of historical fact, and statements on the slides entitled “Highlights”, “The Next Phase – Harnessing Organic Power” and “2026 Financial Outlook”. Such forward-looking statements are based on certain assumptions as of the time they are made, and are inherently subject to known and unknown risks, uncertainties, and other factors, some of which cannot be predicted or quantified, that may cause actual results, performance, or achievements to be materially different from those expressed or implied by such forward-looking statements. Forward-looking statements are often characterized by the use of qualified words (and their derivatives) such as “expect,” “believe,” “estimate,” “plan,” “project,” “anticipate,” “intend,” “will,” “may,” “view,” “opportunity,” “seek to,” “potential,” “continue,” “confidence,” or words of similar meaning or other statements concerning opinions or judgment of Atlantic Union Bankshares Corporation (the “Company,” “AUB,” “we,” “us” or “our”) and our management about future events. Although we believe that our expectations with respect to forward-looking statements are based on reasonable assumptions within the bounds of our existing knowledge of our business and operations, there can be no assurance that actual future results, performance, or achievements of, or trends affecting, us will not differ materially from any projected future results, performance, achievements or trends expressed or implied by such forward-looking statements. Actual future results, performance, achievements or trends may differ materially from historical results or those anticipated depending on a variety of factors, including, but not limited to, the effects of or changes in: • market interest rates and their related impacts on macroeconomic conditions, customer and client behavior, our funding costs and our loan and securities portfolios; • economic conditions, including inflation and recessionary conditions and their related impacts on economic growth and customer and client behavior; • U.S. and global trade policies and tensions, including changes in, or the imposition of, tariffs and/or trade barriers and the economic impacts, volatility and uncertainty resulting therefrom, and geopolitical instability; • volatility in the financial services sector, including failures or rumors of failures of other depository institutions, along with actions taken by governmental agencies to address such turmoil, and the effects on the ability of depository institutions, including us, to attract and retain depositors and to borrow or raise capital; • legislative or regulatory changes and requirements, including changes in federal state or local tax laws and changes impacting the rulemaking, supervision, examination and enforcement priorities of the federal banking agencies; • the sufficiency of liquidity and changes in our capital position; • general economic and financial market conditions in the United States generally and particularly in the markets in which we operate and which our loans are concentrated, including the effects of declines in real estate values, an increase in unemployment levels, U.S. fiscal debt, budget and tax matters, U.S. government shutdowns, and slowdowns in economic growth; • the possibility that the anticipated benefits of our acquisition activity, including anticipated cost savings and strategic gains, are not realized when expected or at all, including as a result of the strength of the economy, competitive factors in the areas where we do business, or as a result of other unexpected factors or events; • potential adverse reactions or changes to business or employee relationships; • our ability to identify, recruit and retain key employees • monetary, fiscal and regulatory policies of the U.S. government, including policies of the U.S. Department of the Treasury and the Federal Reserve; • the quality or composition of our loan or investment portfolios and changes in these portfolios; • demand for loan products and financial services in our market areas; • our ability to manage our growth or implement our growth strategy; • the effectiveness of expense reduction plans; • the introduction of new lines of business or new products and services; • real estate values in our lending area; • changes in accounting principles, standards, rules, and interpretations, and the related impact on our financial statements; • an insufficient ACL or volatility in the ACL resulting from the CECL methodology, either alone or as that may be affected by changing economic conditions, credit concentrations, inflation, changing interest rates, or other factors; • concentrations of loans secured by real estate, particularly commercial real estate; • the effectiveness of our credit processes and management of our credit risk; • our ability to compete in the market for financial services and increased competition from fintech companies; • technological risks and developments, and cyber threats, attacks, or events; • emerging issues related to the development and use of artificial intelligence that could give rise to legal or regulatory action or increase the risk of a cybersecurity attack or the probability that such an attack would be successful; • operational, technological, cultural, regulatory, legal, credit, and other risks associated with the exploration, consummation and integration of potential future acquisitions, whether involving stock or cash consideration; • the potential adverse effects of unusual and infrequently occurring events, such as weather-related disasters, terrorist acts, geopolitical conflicts or public health events (such as pandemics), and of governmental and societal responses thereto; these potential adverse effects may include, without limitation, adverse effects on macroeconomic conditions, the ability of our borrowers to satisfy their obligations to us, on the value of collateral securing loans, on the demand for our loans or our other products and services, on supply chains and methods used to distribute products and services, on incidents of cyberattack and fraud, on our liquidity or capital positions, on risks posed by reliance on third-party service providers, on other aspects of our business operations and on financial markets and economic growth; • performance by our counterparties or vendors; • deposit flows; • the availability of financing and the terms thereof; • the level of prepayments on loans and mortgage-backed securities; • actual or potential claims, damages, and fines related to litigation or government actions, which may result in, among other things, additional costs, fines, penalties, restrictions on our business activities, reputational harm, or other adverse consequences; • any event or development that would cause us to conclude that there was an impairment of any asset, including intangible assets, such as goodwill; and • other factors, many of which are beyond our control. Please also refer to such other factors as discussed throughout Part I, Item 1A. “Risk Factors” and Part II, Item 7. “Management’s Discussion and Analysis of Financial Condition and Results of Operations” of our Annual Report on Form 10-K for the year ended December 31, 2025, and related disclosures in other filings, which have been filed with the U.S. Securities and Exchange Commission (“SEC”) and are available on the SEC’s website at www.sec.gov. All risk factors and uncertainties described herein and therein should be considered in evaluating forward-looking statements, and all forward-looking statements are expressly qualified by the cautionary statements contained or referred to herein and therein. The actual results or developments anticipated may not be realized or, even if substantially realized, they may not have the expected consequences to or effects on the Company or our businesses or operations. Readers are cautioned not to rely too heavily on forward-looking statements. Forward-looking statements speak only as of the date they are made. We do not intend or assume any obligation to update, revise or clarify any forward-looking statements that may be made from time to time by or on behalf of the Company, whether because of new information, future events or otherwise, except as required by law. |
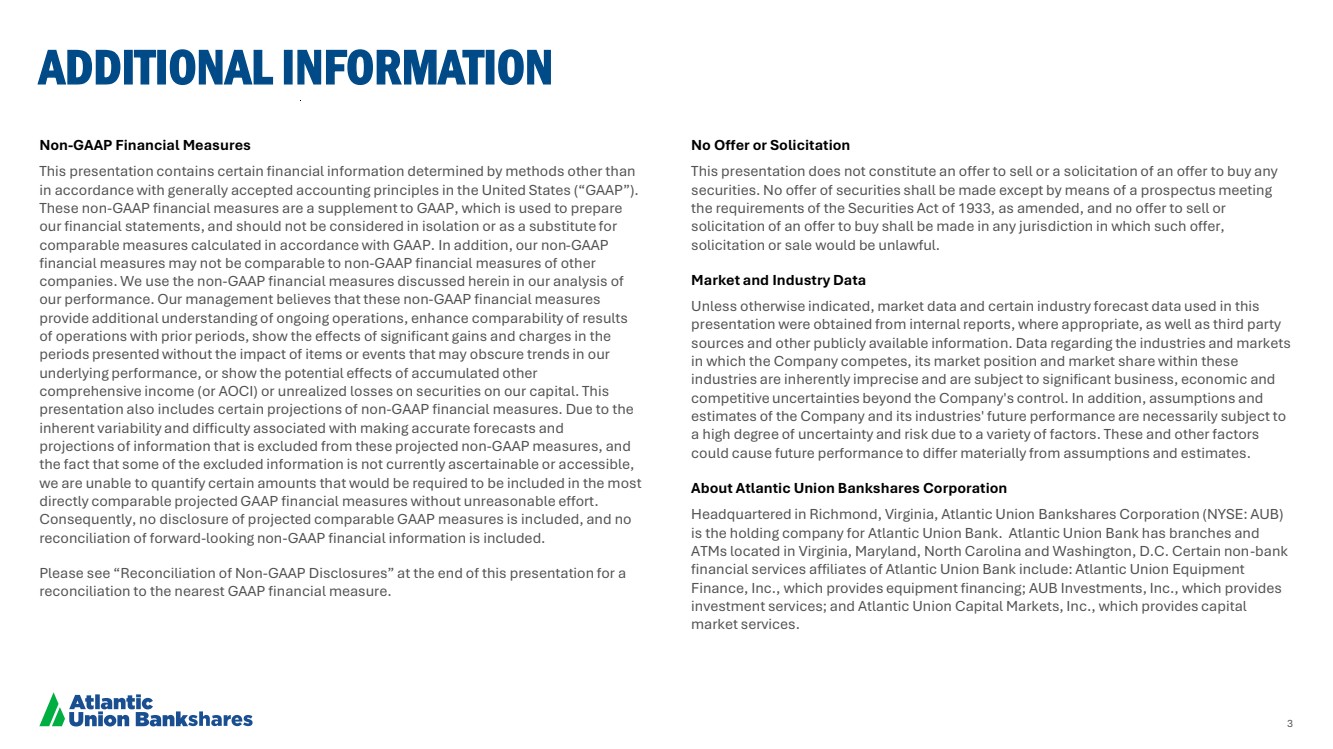
| 3 ADDITIONAL INFORMATION Non-GAAP Financial Measures This presentation contains certain financial information determined by methods other than in accordance with generally accepted accounting principles in the United States (“GAAP”). These non-GAAP financial measures are a supplement to GAAP, which is used to prepare our financial statements, and should not be considered in isolation or as a substitute for comparable measures calculated in accordance with GAAP. In addition, our non-GAAP financial measures may not be comparable to non-GAAP financial measures of other companies. We use the non-GAAP financial measures discussed herein in our analysis of our performance. Our management believes that these non-GAAP financial measures provide additional understanding of ongoing operations, enhance comparability of results of operations with prior periods, show the effects of significant gains and charges in the periods presented without the impact of items or events that may obscure trends in our underlying performance, or show the potential effects of accumulated other comprehensive income (or AOCI) or unrealized losses on securities on our capital. This presentation also includes certain projections of non-GAAP financial measures. Due to the inherent variability and difficulty associated with making accurate forecasts and projections of information that is excluded from these projected non-GAAP measures, and the fact that some of the excluded information is not currently ascertainable or accessible, we are unable to quantify certain amounts that would be required to be included in the most directly comparable projected GAAP financial measures without unreasonable effort. Consequently, no disclosure of projected comparable GAAP measures is included, and no reconciliation of forward-looking non-GAAP financial information is included. Please see “Reconciliation of Non-GAAP Disclosures” at the end of this presentation for a reconciliation to the nearest GAAP financial measure. No Offer or Solicitation This presentation does not constitute an offer to sell or a solicitation of an offer to buy any securities. No offer of securities shall be made except by means of a prospectus meeting the requirements of the Securities Act of 1933, as amended, and no offer to sell or solicitation of an offer to buy shall be made in any jurisdiction in which such offer, solicitation or sale would be unlawful. Market and Industry Data Unless otherwise indicated, market data and certain industry forecast data used in this presentation were obtained from internal reports, where appropriate, as well as third party sources and other publicly available information. Data regarding the industries and markets in which the Company competes, its market position and market share within these industries are inherently imprecise and are subject to significant business, economic and competitive uncertainties beyond the Company's control. In addition, assumptions and estimates of the Company and its industries' future performance are necessarily subject to a high degree of uncertainty and risk due to a variety of factors. These and other factors could cause future performance to differ materially from assumptions and estimates. About Atlantic Union Bankshares Corporation Headquartered in Richmond, Virginia, Atlantic Union Bankshares Corporation (NYSE: AUB) is the holding company for Atlantic Union Bank. Atlantic Union Bank has branches and ATMs located in Virginia, Maryland, North Carolina and Washington, D.C. Certain non-bank financial services affiliates of Atlantic Union Bank include: Atlantic Union Equipment Finance, Inc., which provides equipment financing; AUB Investments, Inc., which provides investment services; and Atlantic Union Capital Markets, Inc., which provides capital market services. |
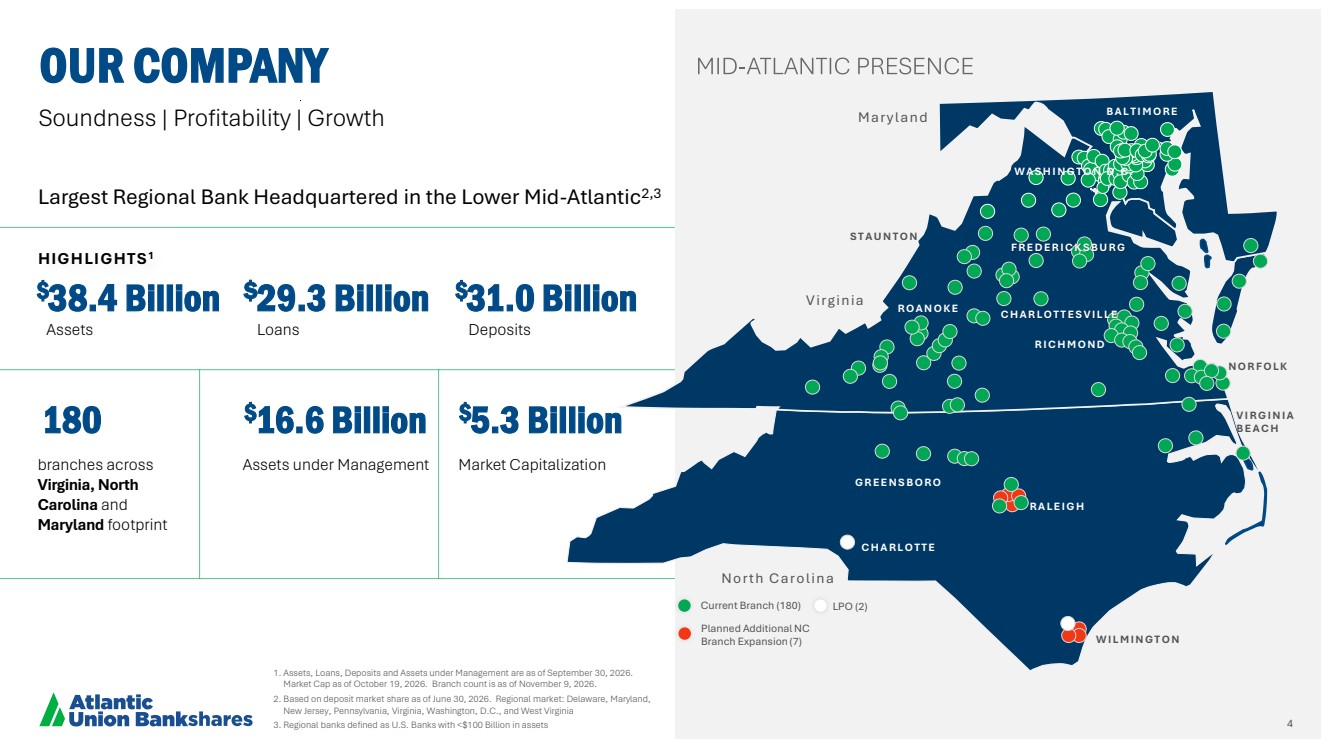
| 4 HIGHLIGHTS1 branches across Virginia, North Carolina and Maryland footprint 180 Assets under Management $16.6 Billion $38.4 Billion Assets $29.3 Billion Loans $31.0 Billion Deposits $5.3 Billion Market Capitalization N O R F O L K V I R G I N I A B E A C H M a ry l a n d V irg in ia No rth C a ro l in a C H A R L O T T E W I L M I N G T O N B A L T I M O R E R A L E I G H G R E E N S B O R O R O A N O K E S T A U N T O N C H A R L O T T E S V I L L E R I C H M O N D F R E D E R I C K S B U R G Current Branch (180) LPO (2) Planned Additional NC Branch Expansion (7) W A S H I N G T O N D . C . OUR COMPANY Soundness | Profitability | Growth Largest Regional Bank Headquartered in the Lower Mid-Atlantic2,3 1. Assets, Loans, Deposits and Assets under Management are as of September 30, 2026. Market Cap as of October 19, 2026. Branch count is as of November 9, 2026. 2. Based on deposit market share as of June 30, 2026. Regional market: Delaware, Maryland, New Jersey, Pennsylvania, Virginia, Washington, D.C., and West Virginia 3. Regional banks defined as U.S. Banks with <$100 Billion in assets 4 |
| 5 Dense, uniquely valuable presence across attractive markets FINANCIAL STRENGTH Solid balance sheet & capital levels PEER-LEADING PERFORMANCE Committed to top-tier financial performance ATTRACTIVE FINANCIAL PROFILE Solid dividend yield & payout ratio with earnings upside STRONG GROWTH POTENTIAL Organic & acquisition opportunities OUR SHAREHOLDER VALUE PROPOSITION Positioned for growth and long-term shareholder value creation as a preeminent regional bank with a leading presence in attractive markets LEADING REGIONAL PRESENCE |
| AUB Q3 2026 FINANCIAL RESULTS |
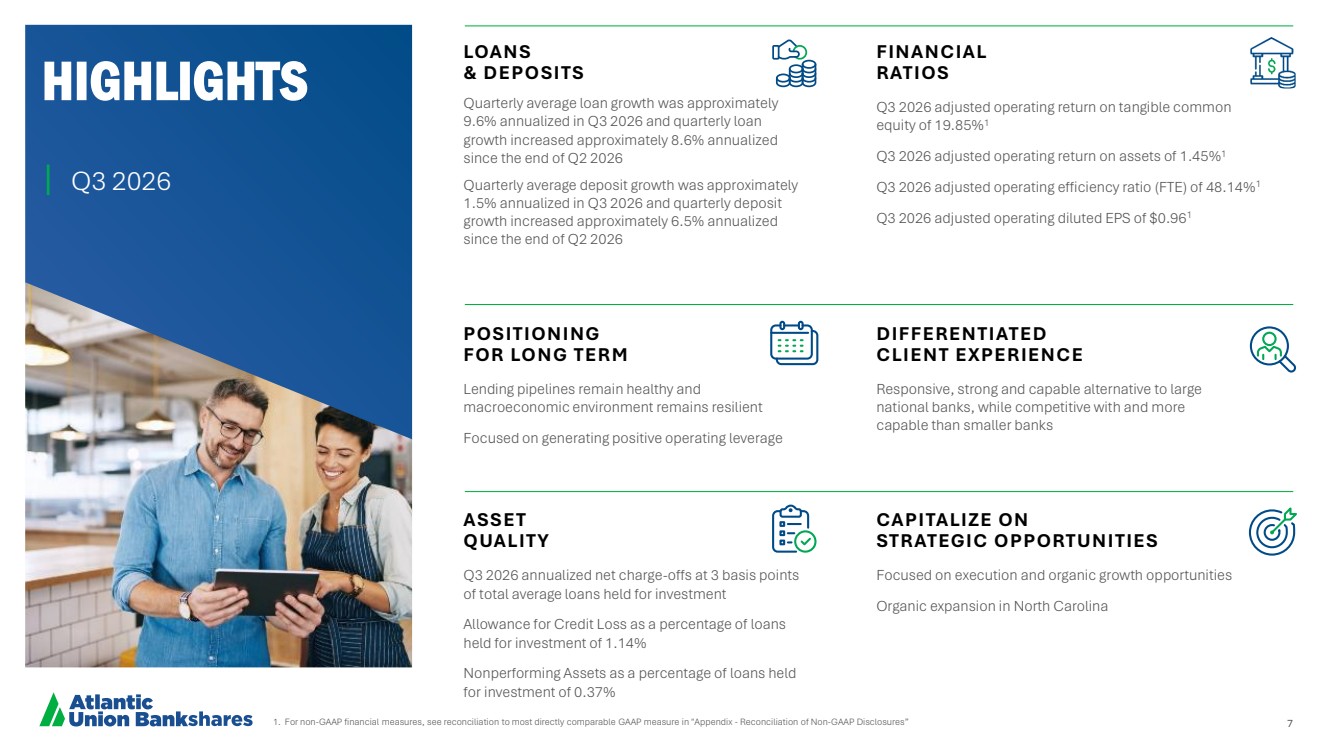
| 1. For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measure in "Appendix - Reconciliation of Non-GAAP Disclosures” 7 HIGHLIGHTS Q3 2026 LOANS & DEPOSITS Quarterly average loan growth was approximately 9.6% annualized in Q3 2026 and quarterly loan growth increased approximately 8.6% annualized since the end of Q2 2026 Quarterly average deposit growth was approximately 1.5% annualized in Q3 2026 and quarterly deposit growth increased approximately 6.5% annualized since the end of Q2 2026 POSITIONING FOR LONG TERM Lending pipelines remain healthy and macroeconomic environment remains resilient Focused on generating positive operating leverage DIFFERENTIATED CLIENT EXPERIENCE Responsive, strong and capable alternative to large national banks, while competitive with and more capable than smaller banks CAPITALIZE ON STRATEGIC OPPORTUNITIES Focused on execution and organic growth opportunities Organic expansion in North Carolina FINANCIAL RATIOS Q3 2026 adjusted operating return on tangible common equity of 19.85%1 Q3 2026 adjusted operating return on assets of 1.45%1 Q3 2026 adjusted operating efficiency ratio (FTE) of 48.14%1 Q3 2026 adjusted operating diluted EPS of $0.961 ASSET QUALITY Q3 2026 annualized net charge-offs at 3 basis points of total average loans held for investment Allowance for Credit Loss as a percentage of loans held for investment of 1.14% Nonperforming Assets as a percentage of loans held for investment of 0.37% 7 |
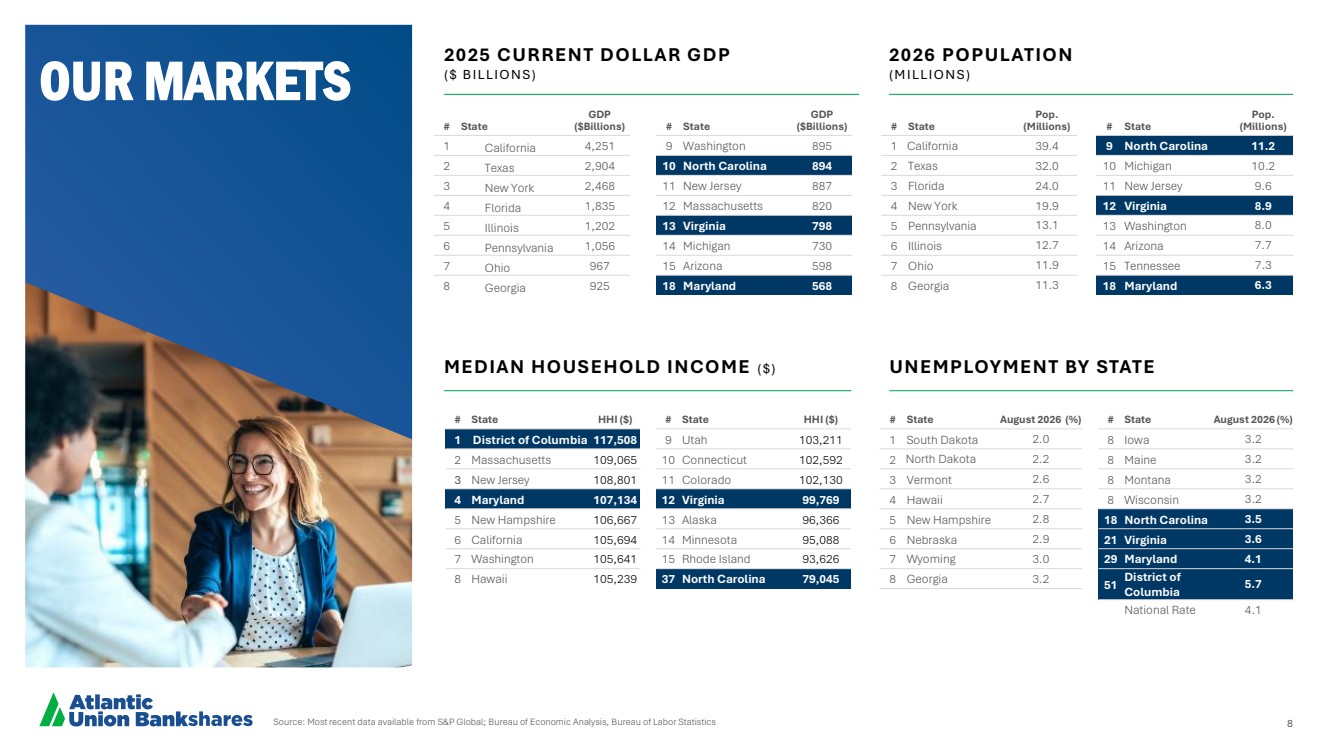
| Source: Most recent data available from S&P Global; Bureau of Economic Analysis, Bureau of Labor Statistics 8 OUR MARKETS # State Pop. (Millions) 1 California 39.4 2 Texas 32.0 3 Florida 24.0 4 New York 19.9 5 Pennsylvania 13.1 6 Illinois 12.7 7 Ohio 11.9 8 Georgia 11.3 # State HHI ($) 1 District of Columbia 117,508 2 Massachusetts 109,065 3 New Jersey 108,801 4 Maryland 107,134 5 New Hampshire 106,667 6 California 105,694 7 Washington 105,641 8 Hawaii 105,239 # State GDP ($Billions) 1 California 4,251 2 Texas 2,904 3 New York 2,468 4 Florida 1,835 5 Illinois 1,202 6 Pennsylvania 1,056 7 Ohio 967 8 Georgia 925 # State Pop. (Millions) 9 North Carolina 11.2 10 Michigan 10.2 11 New Jersey 9.6 12 Virginia 8.9 13 Washington 8.0 14 Arizona 7.7 15 Tennessee 7.3 18 Maryland 6.3 # State HHI ($) 9 Utah 103,211 10 Connecticut 102,592 11 Colorado 102,130 12 Virginia 99,769 13 Alaska 96,366 14 Minnesota 95,088 15 Rhode Island 93,626 37 North Carolina 79,045 # State GDP ($Billions) 9 Washington 895 10 North Carolina 894 11 New Jersey 887 12 Massachusetts 820 13 Virginia 798 14 Michigan 730 15 Arizona 598 18 Maryland 568 MEDIAN HOUSEHOLD INCOME ($) 2026 POPULATION ( M I LLI O N S ) 2025 CURRENT DOLLAR GDP ( $ B I LLI O N S ) UNEMPLOYMENT BY STATE # State August 2026 (%) 1 South Dakota 2.0 2 North Dakota 2.2 3 Vermont 2.6 4 Hawaii 2.7 5 New Hampshire 2.8 6 Nebraska 2.9 7 Wyoming 3.0 8 Georgia 3.2 # State August 2026 (%) 8 Iowa 3.2 8 Maine 3.2 8 Montana 3.2 8 Wisconsin 3.2 18 North Carolina 3.5 21 Virginia 3.6 29 Maryland 4.1 51 District of Columbia 5.7 National Rate 4.1 |
| 9 THE NEXT PHASE HARNESSING ORGANIC POWER With the franchise now established, our focus is on maximizing its potential: We Believe AUB Was Built For This Moment We have invested the capital, built the platform, and assembled the team. Now is the time to demonstrate the power of what we have built— delivering sustainable, top-tier performance and returns. Organic growth Deepening relationships, growing our company organically, and leveraging our scale efficiently. Capital generation Shifting from capital deployment to capital creation, targeting top tier returns, earnings growth, and tangible book value per share growth. Disciplined execution Delivering on the promises made to our stakeholders. |
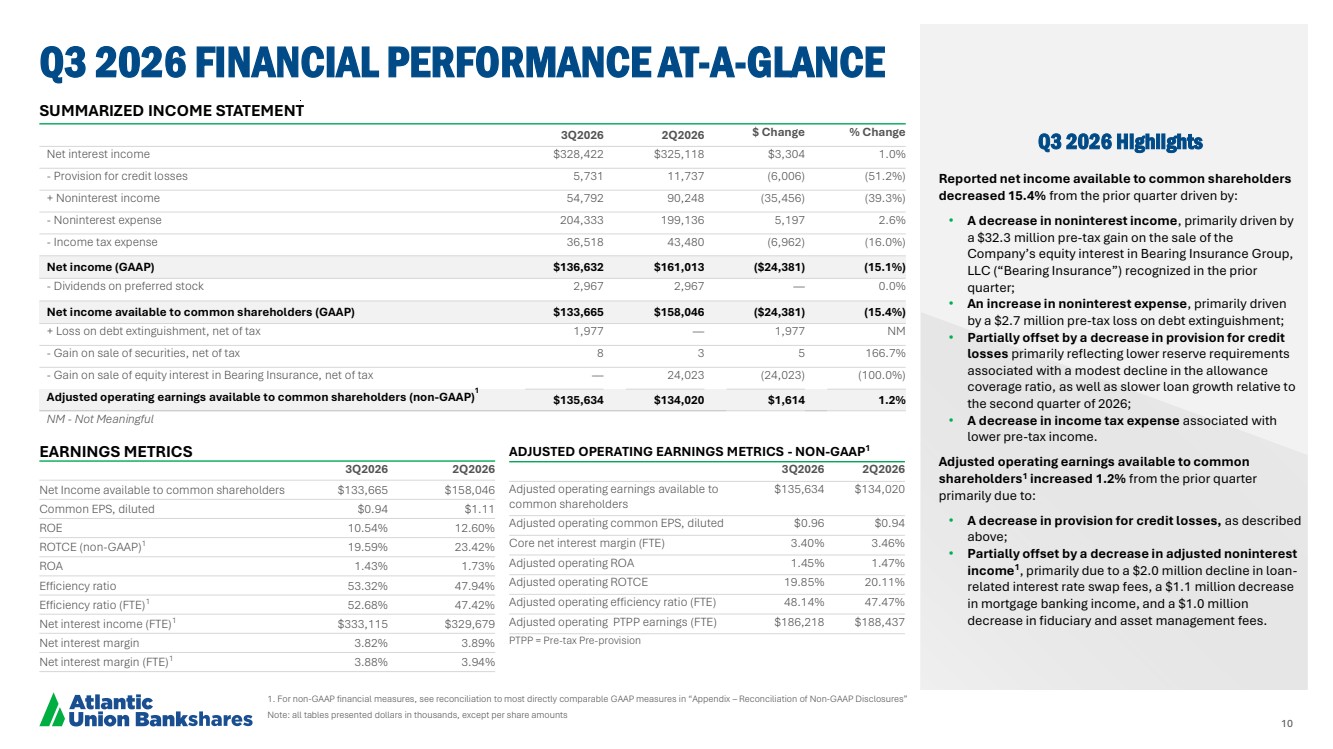
| 10 Q3 2026 Highlights Reported net income available to common shareholders decreased 15.4% from the prior quarter driven by: • A decrease in noninterest income, primarily driven by a $32.3 million pre-tax gain on the sale of the Company’s equity interest in Bearing Insurance Group, LLC (“Bearing Insurance”) recognized in the prior quarter; • An increase in noninterest expense, primarily driven by a $2.7 million pre-tax loss on debt extinguishment; • Partially offset by a decrease in provision for credit losses primarily reflecting lower reserve requirements associated with a modest decline in the allowance coverage ratio, as well as slower loan growth relative to the second quarter of 2026; • A decrease in income tax expense associated with lower pre-tax income. Adjusted operating earnings available to common shareholders1 increased 1.2% from the prior quarter primarily due to: • A decrease in provision for credit losses, as described above; • Partially offset by a decrease in adjusted noninterest income1 , primarily due to a $2.0 million decline in loan-related interest rate swap fees, a $1.1 million decrease in mortgage banking income, and a $1.0 million decrease in fiduciary and asset management fees. 1. For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measures in “Appendix – Reconciliation of Non-GAAP Disclosures” Note: all tables presented dollars in thousands, except per share amounts Q3 2026 FINANCIAL PERFORMANCE AT-A-GLANCE SUMMARIZED INCOME STATEMENT 3Q2026 2Q2026 $ Change % Change Net interest income $328,422 $325,118 $3,304 1.0% - Provision for credit losses 5,731 11,737 (6,006) (51.2%) + Noninterest income 54,792 90,248 (35,456) (39.3%) - Noninterest expense 204,333 199,136 5,197 2.6% - Income tax expense 36,518 43,480 (6,962) (16.0%) Net income (GAAP) $136,632 $161,013 ($24,381) (15.1%) - Dividends on preferred stock 2,967 2,967 — 0.0% Net income available to common shareholders (GAAP) $133,665 $158,046 ($24,381) (15.4%) + Loss on debt extinguishment, net of tax 1,977 — 1,977 NM - Gain on sale of securities, net of tax 8 3 5 166.7% - Gain on sale of equity interest in Bearing Insurance, net of tax — 24,023 (24,023) (100.0%) Adjusted operating earnings available to common shareholders (non-GAAP)1 $135,634 $134,020 $1,614 1.2% NM - Not Meaningful ADJUSTED OPERATING EARNINGS METRICS - NON-GAAP1 3Q2026 2Q2026 Adjusted operating earnings available to common shareholders $135,634 $134,020 Adjusted operating common EPS, diluted $0.96 $0.94 Core net interest margin (FTE) 3.40% 3.46% Adjusted operating ROA 1.45% 1.47% Adjusted operating ROTCE 19.85% 20.11% Adjusted operating efficiency ratio (FTE) 48.14% 47.47% Adjusted operating PTPP earnings (FTE) $186,218 $188,437 PTPP = Pre-tax Pre-provision EARNINGS METRICS 3Q2026 2Q2026 Net Income available to common shareholders $133,665 $158,046 Common EPS, diluted $0.94 $1.11 ROE 10.54% 12.60% ROTCE (non-GAAP)1 19.59% 23.42% ROA 1.43% 1.73% Efficiency ratio 53.32% 47.94% Efficiency ratio (FTE)1 52.68% 47.42% Net interest income (FTE)1 $333,115 $329,679 Net interest margin 3.82% 3.89% Net interest margin (FTE)1 3.88% 3.94% |
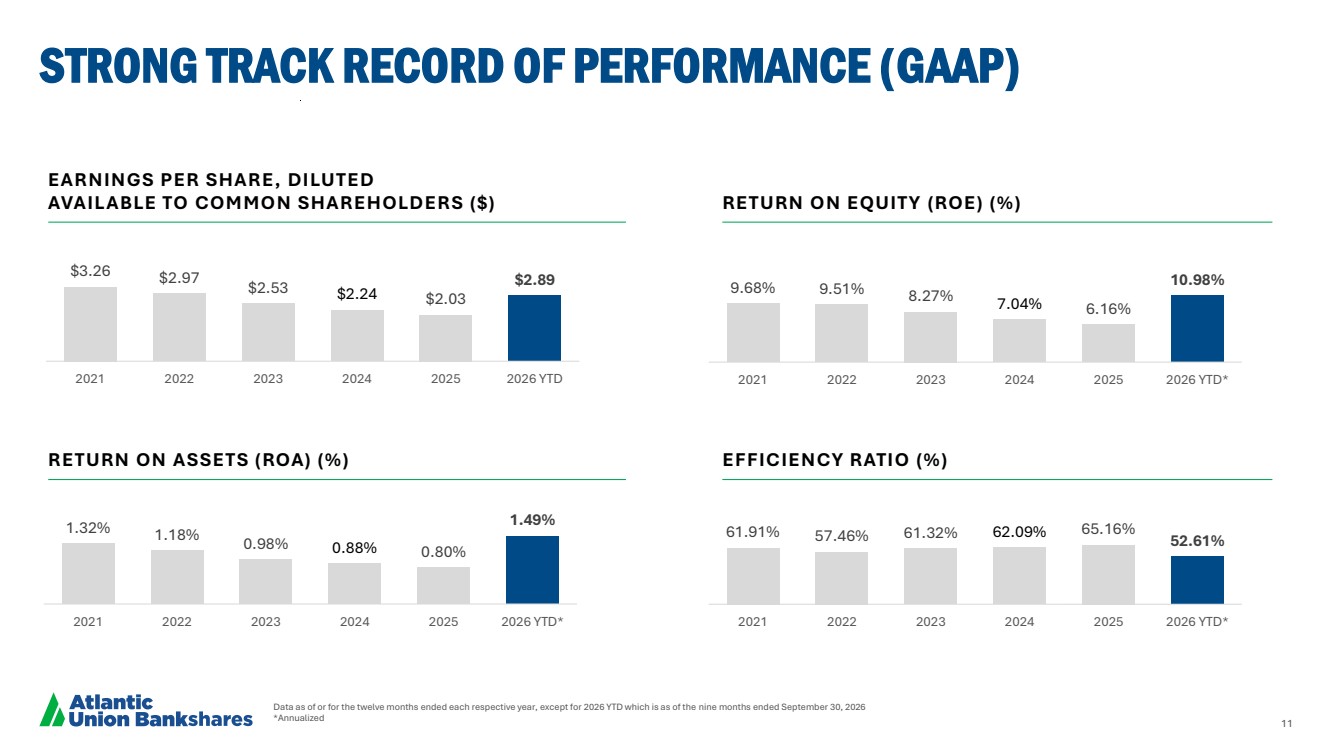
| 11 Data as of or for the twelve months ended each respective year, except for 2026 YTD which is as of the nine months ended September 30, 2026 *Annualized STRONG TRACK RECORD OF PERFORMANCE (GAAP) $3.26 $2.97 $2.53 $2.24 $2.03 $2.89 2021 2022 2023 2024 2025 2026 YTD 9.68% 9.51% 8.27% 7.04% 6.16% 10.98% 2021 2022 2023 2024 2025 2026 YTD* 61.91% 57.46% 61.32% 62.09% 65.16% 52.61% 2021 2022 2023 2024 2025 2026 YTD* 1.32% 1.18% 0.98% 0.88% 0.80% 1.49% 2021 2022 2023 2024 2025 2026 YTD* EARNINGS PER SHARE, DILUTED AVAILABLE TO COMMON SHAREHOLDERS ($) RETURN ON EQUITY (ROE) (%) RETURN ON ASSETS (ROA) (%) EFFICIENCY RATIO (%) |
| 12 STRONG TRACK RECORD OF PERFORMANCE (NON-GAAP) Data as of or for the twelve months ended each respective year, except 2026 YTD which is as of the nine months ended September 30, 2026 * Annualized (1) Non-GAAP financial measure; See reconciliation to most directly comparable GAAP measure in "Appendix -- Reconciliation of Non-GAAP Disclosures” ADJUSTED OPERATING EARNINGS PER SHARE AVAILABLE TO COMMON SHAREHOLDERS, DILUTED ($)(1) ADJUSTED OPERATING RETURN ON TANGIBLE COMMON EQUITY (ROTCE) (%)(1) ADJUSTED OPERATING RETURN ON ASSETS (ROA) (%)(1) ADJUSTED OPERATING EFFICIENCY RATIO (FTE)(%)(1) $3.53 $2.92 $2.95 $2.88 $3.44 $2.79 2021 2022 2023 2024 2025 2026 YTD 18.07% 17.06% 17.21% 16.85% 20.41% 19.86% 2021 2022 2023 2024 2025 2026 YTD* 54.52% 54.68% 54.15% 53.31% 49.68% 48.47% 2021 2022 2023 2024 2025 2026 YTD* 1.43% 1.16% 1.14% 1.11% 1.33% 1.44% 2021 2022 2023 2024 2025 2026 YTD* |
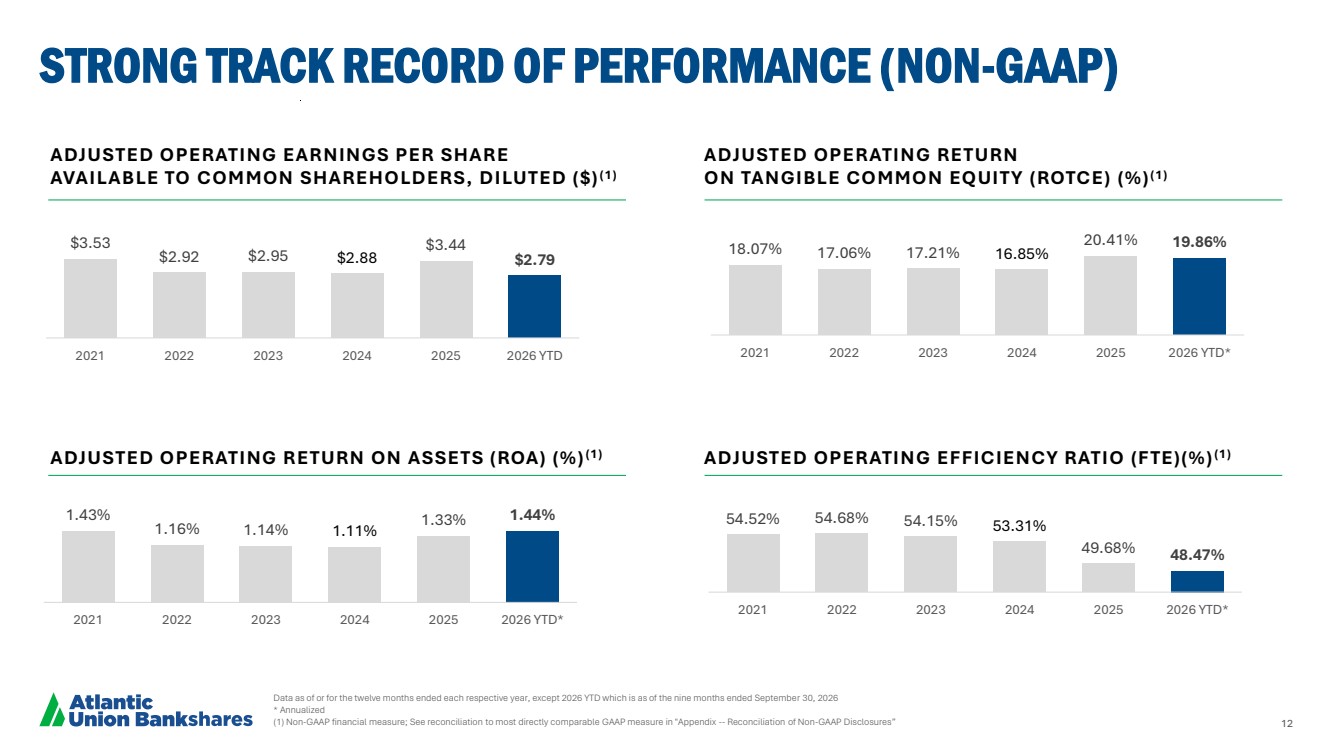
| 13 Numbers may not foot due to rounding Q3 2026 ALLOWANCE FOR CREDIT LOSSES (ACL) AND PROVISION FOR CREDIT LOSSES Q3 MACROECONOMIC FORECAST Q3 ACL CONSIDERATIONS MOODY’S SEPTEMBER 2026 BASELINE FORECAST: • US GDP expected to average ~2.2% growth in 2026 and ~2.0% in 2027. • The national unemployment rate expected to average ~4.3% in 2026 and ~4.6% in 2027. • Utilizes a weighted Moody’s forecast economic scenarios approach in the overall estimate. • The increase in the allowance for credit losses reflects loan growth and increased reserves on unfunded commitments particularly in the Construction and Land Development portfolio. • The reasonable and supportable forecast period is 2 years; followed by reversion to the historical loss average over 2 years. ALLOWANCE FOR LOAN & LEASE LOSSES (ALLL) RESERVE FOR UNFUNDED COMMITMENTS (RUC) ALLOWANCE FOR CREDIT LOSSES 03/31/2026 Ending Balance % of loans $291.1 million (1.04%) $30.8 million (0.11%) $321.9 million (1.15%) Q2 2026 Activity +$7.7 million Increase driven by loan growth. +$1.4 million Increase driven by growth in unfunded commitments. +$9.1 million $11.0 million Provision for Credit Losses and $2.0 million net charge-offs. 06/30/2026 Ending Balance % of loans $298.8 million (1.04%) $32.2 million (0.11%) $331.0 million (1.15%) Q3 2026 Activity +$2.6 million Increase driven by loan growth. +$0.6 million Increase driven by growth in reserve for unfunded commitments within the Construction and Land Development portfolio. +$3.3 million $5.7 million Provision for Credit Losses and $2.3 million net charge-offs. 09/30/2026 Ending Balance % of loans $301.4 million (1.03%) $32.8 million (0.11%) $334.2 million (1.14%) |
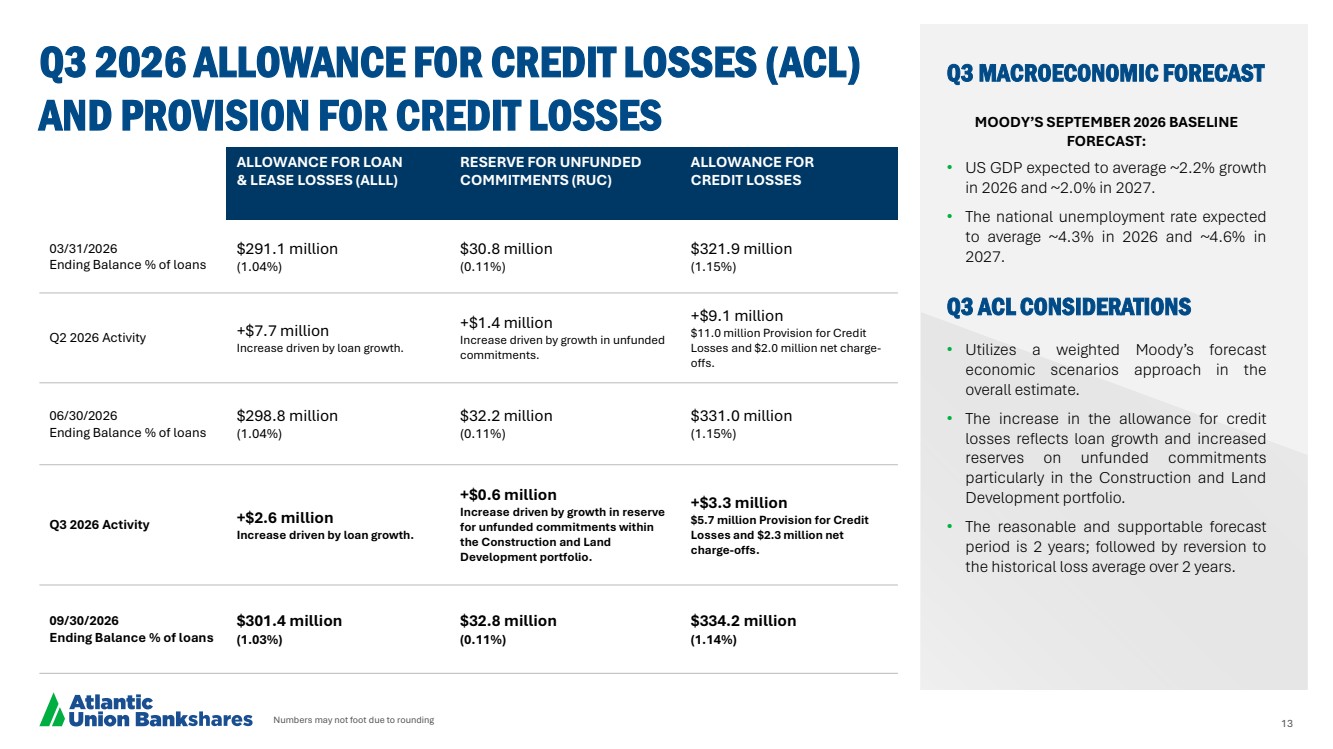
| 14 Q2 2026 Reported NIM Earning Assets Mix Deposit Cost Borrowing Cost Funding Mix Q3 2026 Reported NIM NET INTEREST MARGIN (FTE)1 : DRIVERS OF CHANGE Q2 2026 TO Q3 2026 1. For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measures in “Appendix – Reconciliation of Non-GAAP Disclosures” Numbers may not foot due to rounding 2. Source Bloomberg Q3 2026 NET INTEREST MARGIN MARKET RATES2 Q3 2026 Q2 2026 EOP Avg EOP Avg Fed funds 4.00% 3.79% 3.75% 3.75% Prime 7.00% 6.79% 6.75% 6.75% 1-month SOFR 3.91% 3.73% 3.65% 3.64% 2-year Treasury 4.89% 4.36% 4.17% 3.97% 5-year Treasury 5.09% 4.50% 4.23% 4.09% 10- year Treasury 5.28% 4.74% 4.47% 4.41% MARGIN OVERVIEW Q3 2026 Q2 2026 Net interest margin (FTE)1 3.88% 3.94% Loan yield (FTE)1 6.22% 6.23% Investment yield (FTE)1 4.05% 4.05% Earning asset yield (FTE)1 5.89% 5.88% Cost of deposits 2.00% 1.93% Cost of interest-bearing deposits 2.55% 2.48% Cost of interest-bearing liabilities 2.68% 2.59% Cost of funds 2.01% 1.94% Presented on an FTE basis (non-GAAP)1 Approximately 19% of the total loan portfolio at 9/30/2026 have floors and all are above floors LOAN PORTFOLIO PRICING MIX Q3 2026 Fixed 46% 1-month SOFR 42% Prime 8% Other 5% Total 100% -4 bps 1 bp 3.88% -2 bps - 1 bp 3.94% |
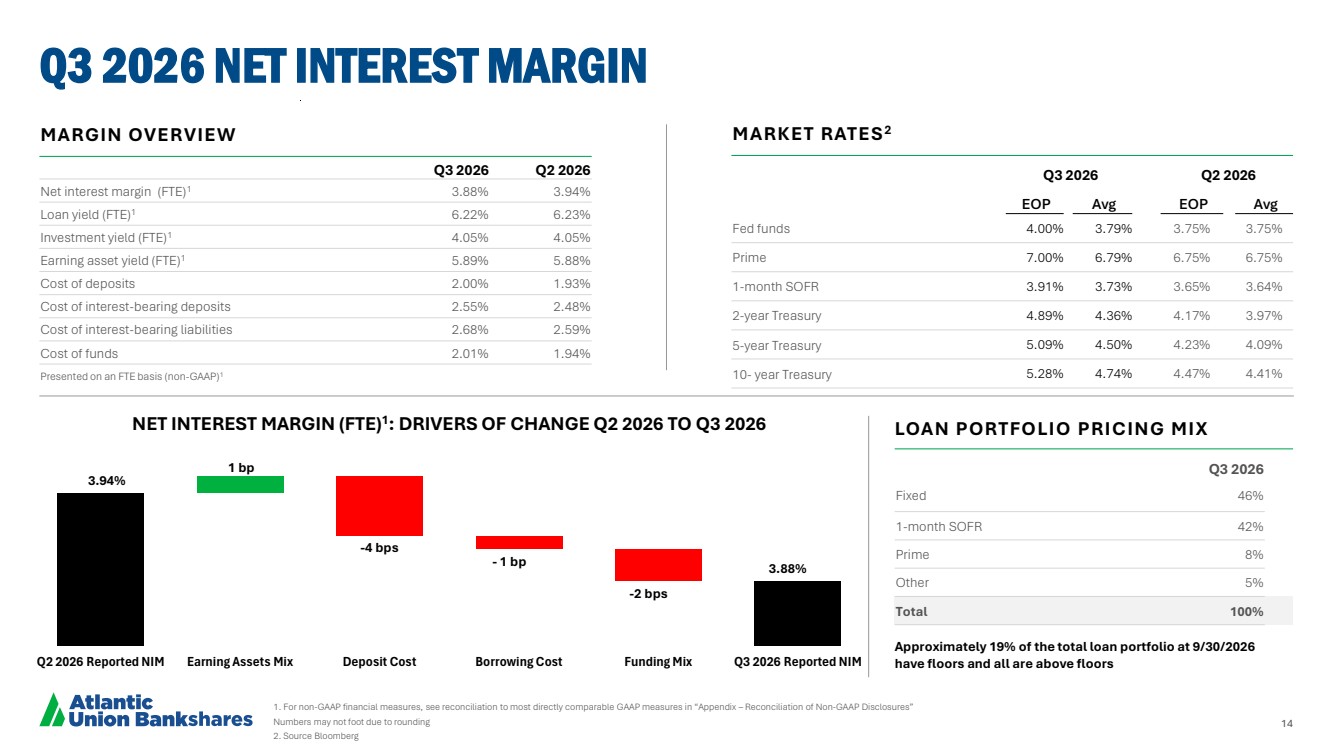
| 1. For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measures in “Appendix – Reconciliation of Non-GAAP Disclosures” 15 Q3 2026 NONINTEREST INCOME Noninterest income decreased approximately 39.3% in the third quarter of 2026 compared to the second quarter of 2026 primarily due to: • A $32.3 million pre-tax gain on the sale of the Company’s equity interest in Bearing Insurance, recognized within other operating income in the prior quarter. Adjusted operating noninterest income1 decreased approximately 5.4% in the third quarter of 2026 compared to the second quarter of 2026 primarily due to: • A $2.0 million decline in loan-related interest rate swap fees driven by lower transaction volumes; • A $1.1 million decrease in mortgage banking income due to lower mortgage origination volumes and lower gain on sale margins; • A $1.0 million decrease in fiduciary and asset management fees. ($ THOUSANDS) 3Q2026 2Q2026 $ Change % Change Service charges on deposit accounts $12,886 $12,259 $627 5.1% Other service charges, commissions and fees 2,266 2,286 (20) (0.9%) Interchange fees 3,697 3,750 (53) (1.4%) Fiduciary and asset management fees 20,452 21,460 (1,008) (4.7%) Mortgage banking income 1,528 2,656 (1,128) (42.5%) Bank owned life insurance income 5,954 5,734 220 3.8% Loan-related interest rate swap fees 4,530 6,484 (1,954) (30.1%) Other operating income 3,479 35,619 (32,140) (90.2%) Total noninterest income $54,792 $90,248 ($35,456) (39.3%) Less: Gain on sale of securities 10 4 6 150.0% Less: Gain on sale of equity interest in Bearing Insurance — 32,350 (32,350) (100.0%) Adjusted operating noninterest income (non-GAAP)1 $54,782 $57,894 ($3,112) (5.4%) |
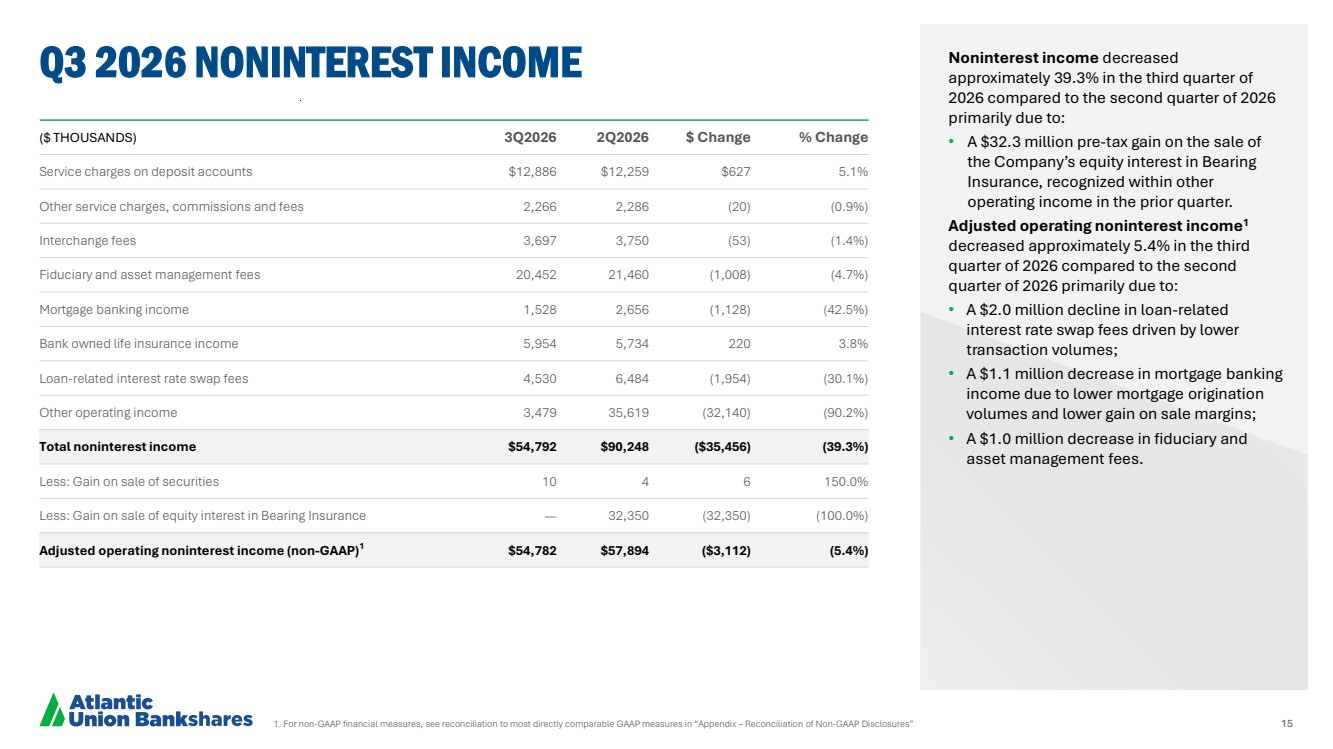
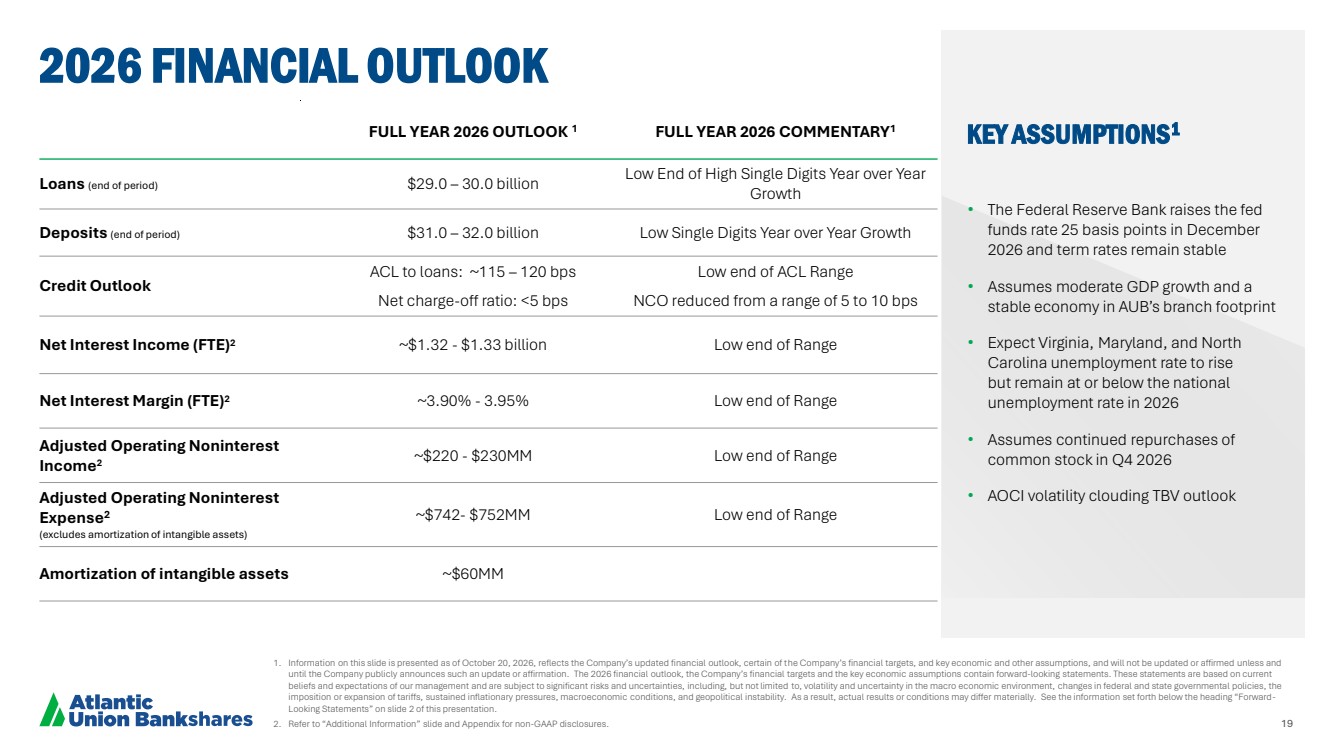
| 1. For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measures in “Appendix – Reconciliation of Non-GAAP Disclosures” 16 Q3 2026 NONINTEREST EXPENSE Noninterest expense increased 2.6% in the third quarter of 2026 compared to the second quarter of 2026 primarily due to: • A $2.7 million pre-tax loss on debt extinguishment. Adjusted operating noninterest expense1 increased 1.5% in the third quarter of 2026 compared to the second quarter of 2026 primarily due to: • A $2.6 million seasonal increase in marketing and advertising expense; • A $1.7 million increase in salaries and benefits expense, primarily due to an increase in variable incentive compensation expense and additional full-time equivalent employees associated with the Company’s North Carolina expansion; • A $1.5 million increase in technology and data processing expense, primarily reflecting ongoing investments in strategic technology initiatives and related software maintenance costs; • Partially offset by a $3.4 million decrease in other expenses, primarily driven by gains on sales of other real estate owned during the third quarter of 2026. ($ THOUSANDS) 3Q2026 2Q2026 $ Change % Change Salaries and benefits $113,978 $112,309 $1,669 1.5% Occupancy expenses 13,089 12,862 227 1.8% Furniture and equipment expenses 5,604 5,532 72 1.3% Technology and data processing 17,492 16,016 1,476 9.2% Professional services 6,193 6,154 39 0.6% Marketing and advertising expense 8,040 5,479 2,561 46.7% FDIC assessment premiums and other insurance 6,759 6,633 126 1.9% Franchise and other taxes 4,767 4,675 92 2.0% Loan-related expenses 2,544 2,723 (179) (6.6%) Amortization of intangible assets 14,946 15,136 (190) (1.3%) Other expenses 10,921 11,617 (696) (6.0%) Total noninterest expense $204,333 $199,136 $5,197 2.6% Less: Amortization of intangible assets 14,946 15,136 (190) (1.3%) Less: Loss on debt extinguishment 2,654 — 2,654 NM Adjusted operating noninterest expense (non-GAAP)1 $186,733 $184,000 $2,733 1.5% NM - Not Meaningful |
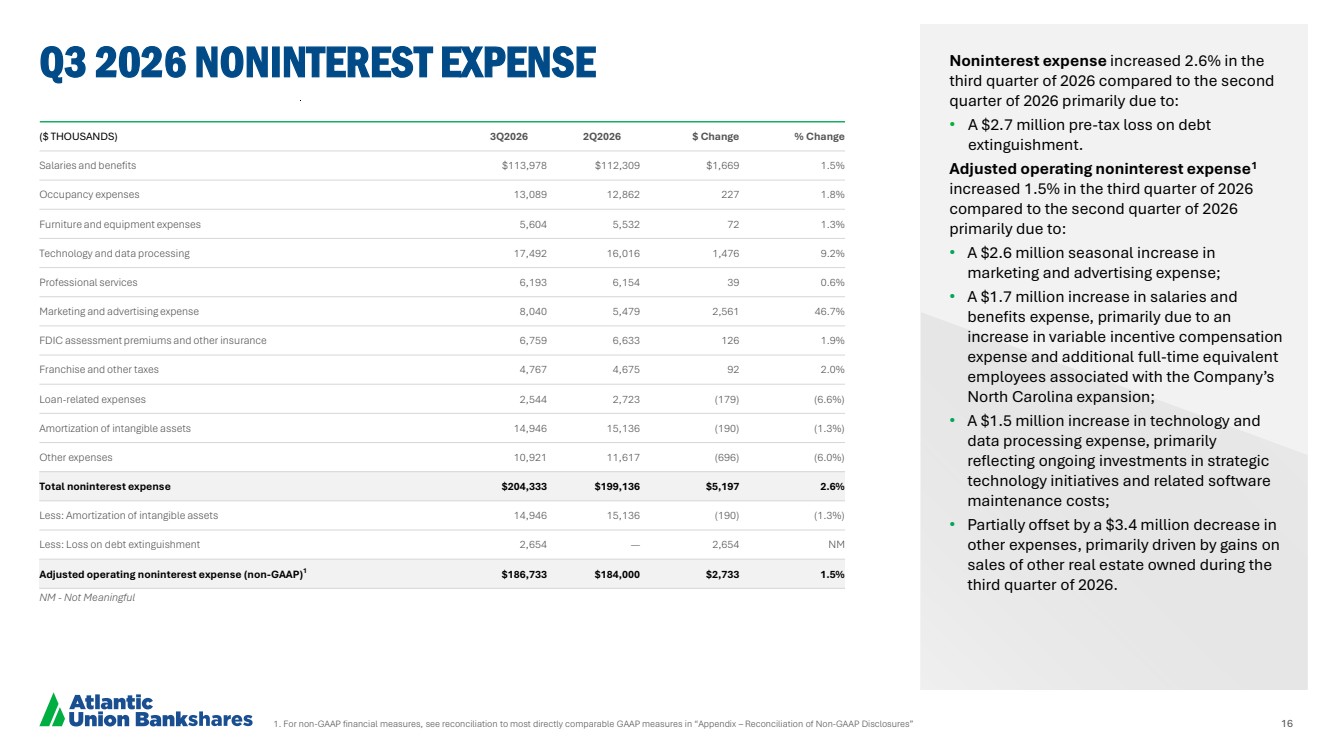
| 17 Q3 2026 LOANS AND DEPOSITS • At September 30, 2026, LHFI totaled $29.3 billion, an increase of $623.3 million from the prior quarter primarily due to increases in commercial and industrial, other commercial, and construction and land development loan portfolios. • Average loan yields (FTE)2 decreased 1 basis point to 6.22%. • At September 30, 2026, total deposits were $31.0 billion, an increase of $497.3 million from the prior quarter due to increases in brokered and demand deposits, partially offset by a decrease in interest-bearing customer deposits. • Noninterest-bearing demand deposits accounted for 22% of total deposit balances at the end of the third quarter of 2026, in line with the prior quarter. • The average cost of deposits increased by 7 basis points compared to the prior quarter, resulting from increased costs on customer interest-bearing deposits and higher brokered deposit costs. • At September 30, 2026, the loan to deposit ratio was 94.6%, up from 94.1% in the prior quarter. (1) Auto portfolio is in run-off mode. (2) For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measures in “Appendix – Reconciliation of Non-GAAP Disclosures” LOANS ($ THOUSANDS) 3Q2026 2Q2026 QTD ANNUALIZED % CHANGE Commercial real estate - non-owner occupied $ 7,275,895 $ 7,303,555 (1.5%) Commercial real estate - owner occupied 4,356,099 4,308,292 4.4% Construction and land development 2,025,385 1,859,217 35.5% Multifamily real estate 2,382,541 2,429,355 (7.6%) Residential 1-4 Family - Commercial 984,149 1,008,438 (9.6%) Total Commercial Real Estate (CRE) 17,024,069 16,908,857 2.7% Commercial & Industrial 5,850,846 5,628,880 15.6% Other Commercial 1,865,561 1,649,952 51.8% Total Commercial & Industrial 7,716,407 7,278,832 23.9% Total Commercial Loans $ 24,740,476 $ 24,187,689 9.1% Residential 1-4 Family - Consumer 2,991,674 2,930,665 8.3% Residential 1-4 Family - Revolving 1,346,890 1,312,531 10.4% Auto(1) 110,418 131,477 (63.5%) Consumer 107,158 110,909 (13.4%) Total Consumer Loans $ 4,556,140 $ 4,485,582 6.2% Total Loans Held for Investment (LHFI) (net of unearned income) $ 29,296,616 $ 28,673,271 8.6% Average Loan Yield (FTE) 6.22% 6.23% DEPOSITS ($ THOUSANDS) 3Q2026 2Q2026 QTD ANNUALIZED % CHANGE Interest checking accounts $ 7,844,500 $ 7,812,504 1.6% Money market accounts 6,556,864 6,821,997 (15.4%) Savings accounts 2,723,123 2,567,073 24.1% Customer time deposits of more than $250,000 1,869,330 1,876,425 (1.5%) Customer time deposits of $250,000 or less 4,124,050 4,104,769 1.9% Time deposits 5,993,380 5,981,194 0.8% Total interest-bearing customer deposits 23,117,867 23,182,768 (1.1%) Brokered deposits 1,085,988 557,751 375.7% Total interest-bearing deposits 24,203,855 23,740,519 7.7% Demand deposits 6,761,674 6,727,738 2.0% Total Deposits $ 30,965,529 $ 30,468,257 6.5% Average Cost of Deposits 2.00% 1.93% Loan to Deposit Ratio 94.6% 94.1% |
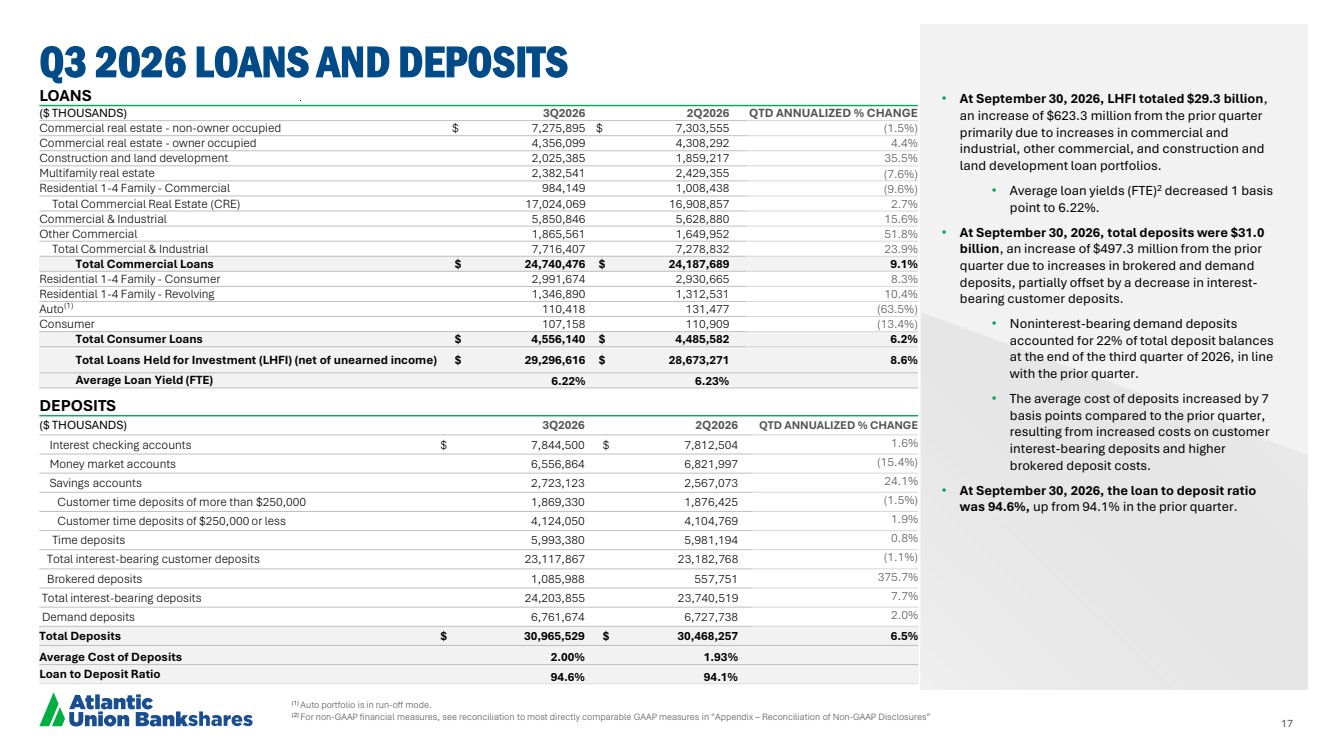
| 18 CAPITAL RATIO REGULATORY WELL CAPITALIZED MINIMUMS REPORTED PRO FORMA INCLUDING AOCI & HTM UNREALIZED LOSSES ATLANTIC UNION BANKSHARES ATLANTIC UNION BANK ATLANTIC UNION BANKSHARES ATLANTIC UNION BANK Common Equity Tier 1 Ratio (CET1) 6.5% 10.4% 13.4% 8.9% 11.8% Tier 1 Capital Ratio 8.0% 10.9% 13.4% 9.4% 11.8% Total Risk Based Capital Ratio 10.0% 14.6% 14.3% 13.0% 12.8% Leverage Ratio 5.0% 9.6% 11.7% 8.3% 10.4% Tangible Equity to Tangible Assets (non-GAAP)1 - 8.3% 10.5% 8.1% 10.2% Tangible Common Equity Ratio(non-GAAP) 1 - 7.9% 10.5% 7.6% 10.2% As of 9/30/2026 As of 9/30/2025 % Change Tangible Book Value per share (non-GAAP) 1 Ex. AOCI $23.22 $20.98 10.7% 1. For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measures in “Appendix – Reconciliation of Non-GAAP Disclosures” • Capital information presented herein is based on estimates and subject to change pending the Company’s filing of its regulatory reports • Figures may not foot due to rounding STRONG CAPITAL POSITION CAPITAL MANAGEMENT STRATEGY ATLANTIC UNION CAPITAL MANAGEMENT OBJECTIVES ARE TO: • Maintain designation as a “well capitalized” institution. • Ensure capital levels are commensurate with the Company’s risk profile, capital stress test projections, and strategic plan objectives. THE COMPANY’S CAPITAL RATIOS ARE WELL ABOVE REGULATORY WELL CAPITALIZED LEVELS AS OF SEPTEMBER 30, 2026 • On a pro forma standalone basis, the Company and the Bank would be well capitalized if unrealized losses on securities were realized at September 30, 2026. CAPITAL MANAGEMENT ACTIONS During the third quarter of 2026, the Company: • Paid a common stock dividend of 37 cents per share, which was the same as the second quarter of 2026, and an increase of 8.8% from the third quarter of 2025 dividend amount. • Paid dividends of $171.88 per outstanding share of Series A Preferred Stock • Repurchased $62.5 million of common stock at an average price of $41.38 At September 30, 2026 QUARTERLY ROLL FORWARD COMMON EQUITY TIER 1 RATIO TANGIBLE COMMON EQUITY RATIO TANGIBLE BOOK VALUE PER SHARE 6/30/26 10.41% 8.17% $20.77 Pre-Provision Net Income 0.45% 0.39% 0.99 One-Time impacts (0.01%) (0.01%) (0.01) After Tax Provision (0.01%) (0.01%) (0.03) Common Dividend (0.17%) (0.15%) (0.37) Common Share Repurchases (0.20%) (0.17%) (0.23) AOCI 0.00% (0.35%) (0.89) Goodwill & Intangibles 0.04% 0.04% 0.11 Deferred Taxes and Other 0.04% 0.01% 0.03 Asset Growth (0.16%) (0.06%) 0.00 9/30/26 10.39% 7.87% $20.36 AOCI Total Impact --- 1.11% 2.87 9/30/26 ex. AOCI 10.39% 8.98% $23.22 |
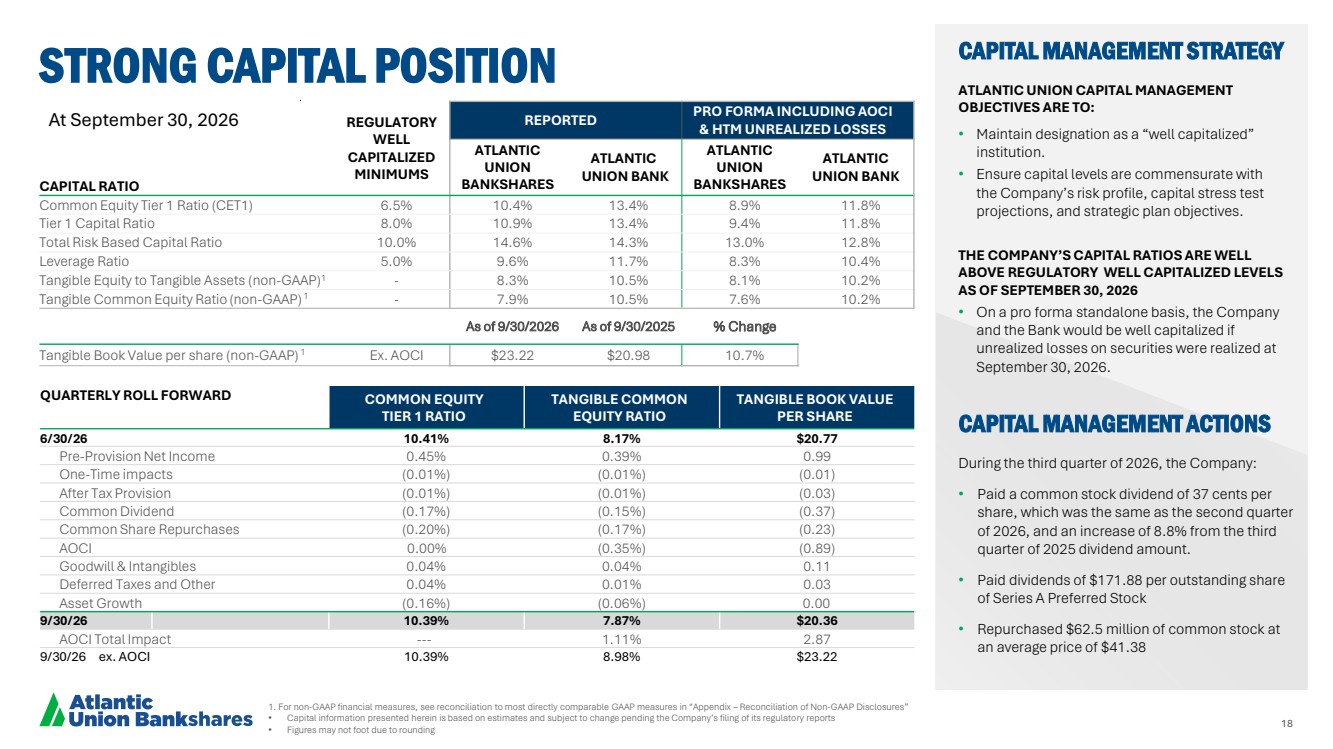
| 19 2026 FINANCIAL OUTLOOK 1. Information on this slide is presented as of October 20, 2026, reflects the Company’s updated financial outlook, certain of the Company’s financial targets, and key economic and other assumptions, and will not be updated or affirmed unless and until the Company publicly announces such an update or affirmation. The 2026 financial outlook, the Company’s financial targets and the key economic assumptions contain forward-looking statements. These statements are based on current beliefs and expectations of our management and are subject to significant risks and uncertainties, including, but not limited to, volatility and uncertainty in the macro economic environment, changes in federal and state governmental policies, the imposition or expansion of tariffs, sustained inflationary pressures, macroeconomic conditions, and geopolitical instability. As a result, actual results or conditions may differ materially. See the information set forth below the heading “Forward-Looking Statements” on slide 2 of this presentation. 2. Refer to “Additional Information” slide and Appendix for non-GAAP disclosures. FULL YEAR 2026 OUTLOOK 1 FULL YEAR 2026 COMMENTARY1 Loans (end of period) $29.0 – 30.0 billion Low End of High Single Digits Year over Year Growth Deposits (end of period) $31.0 – 32.0 billion Low Single Digits Year over Year Growth Credit Outlook ACL to loans: ~115 – 120 bps Net charge-off ratio: <5 bps Low end of ACL Range NCO reduced from a range of 5 to 10 bps Net Interest Income (FTE)2 ~$1.32 - $1.33 billion Low end of Range Net Interest Margin (FTE)2 ~3.90% - 3.95% Low end of Range Adjusted Operating Noninterest Income2 ~$220 - $230MM Low end of Range Adjusted Operating Noninterest Expense2 (excludes amortization of intangible assets) ~$742- $752MM Low end of Range Amortization of intangible assets ~$60MM • The Federal Reserve Bank raises the fed funds rate 25 basis points in December 2026 and term rates remain stable • Assumes moderate GDP growth and a stable economy in AUB’s branch footprint • Expect Virginia, Maryland, and North Carolina unemployment rate to rise but remain at or below the national unemployment rate in 2026 • Assumes continued repurchases of common stock in Q4 2026 • AOCI volatility clouding TBV outlook KEY ASSUMPTIONS1 |
| Q3 2026 APPENDIX |
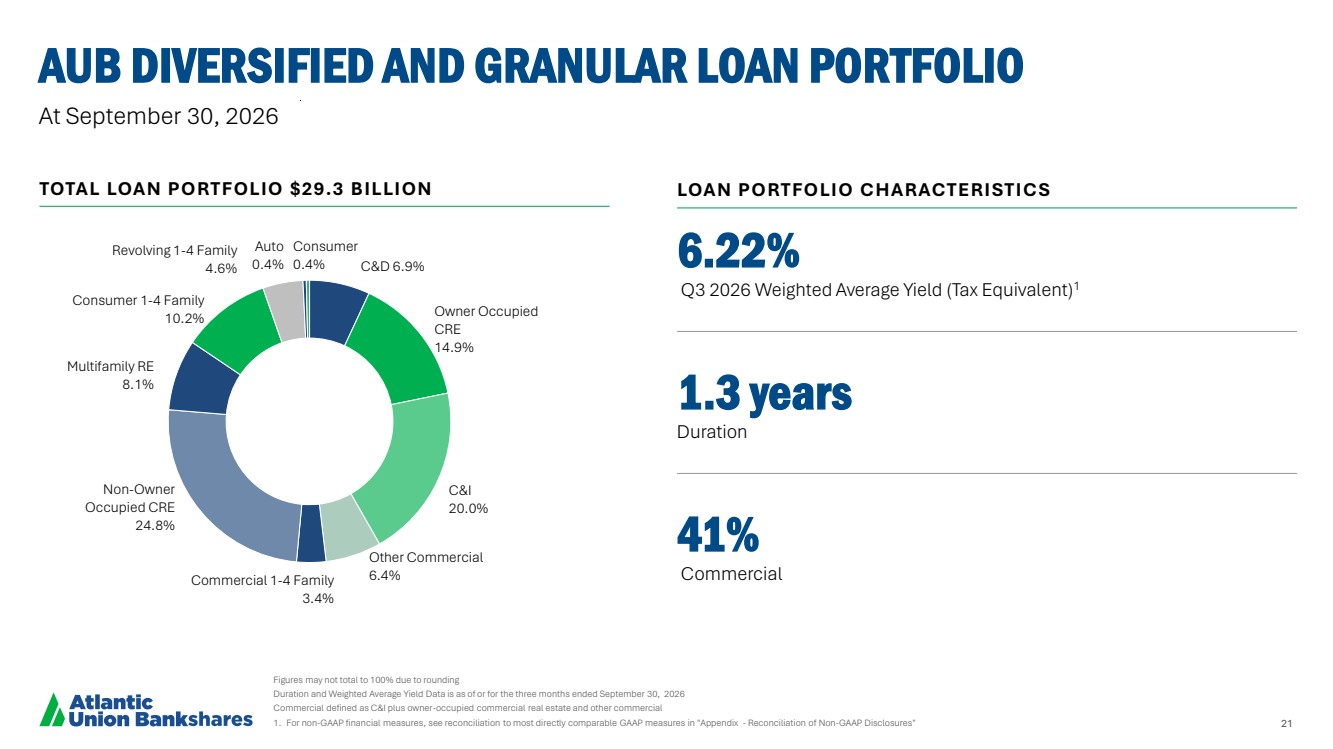
| 21 AUB DIVERSIFIED AND GRANULAR LOAN PORTFOLIO Figures may not total to 100% due to rounding Duration and Weighted Average Yield Data is as of or for the three months ended September 30, 2026 Commercial defined as C&I plus owner-occupied commercial real estate and other commercial 1. For non-GAAP financial measures, see reconciliation to most directly comparable GAAP measures in "Appendix - Reconciliation of Non-GAAP Disclosures" Duration Q2 2025 Weighted Average Yield (Tax Equivalent) C&D 6.9% Owner Occupied CRE 14.9% C&I 20.0% Other Commercial Commercial 1-4 Family 6.4% 3.4% Non-Owner Occupied CRE 24.8% Multifamily RE 8.1% Consumer 1-4 Family 10.2% Revolving 1-4 Family 4.6% Auto 0.4% Consumer 0.4% TOTAL LOAN PORTFOLIO $29.3 BILLION At September 30, 2026 LOAN PORTFOLIO CHARACTERISTICS 1.3 years Duration 41% Commercial 6.22% Q3 2026 Weighted Average Yield (Tax Equivalent)1 |
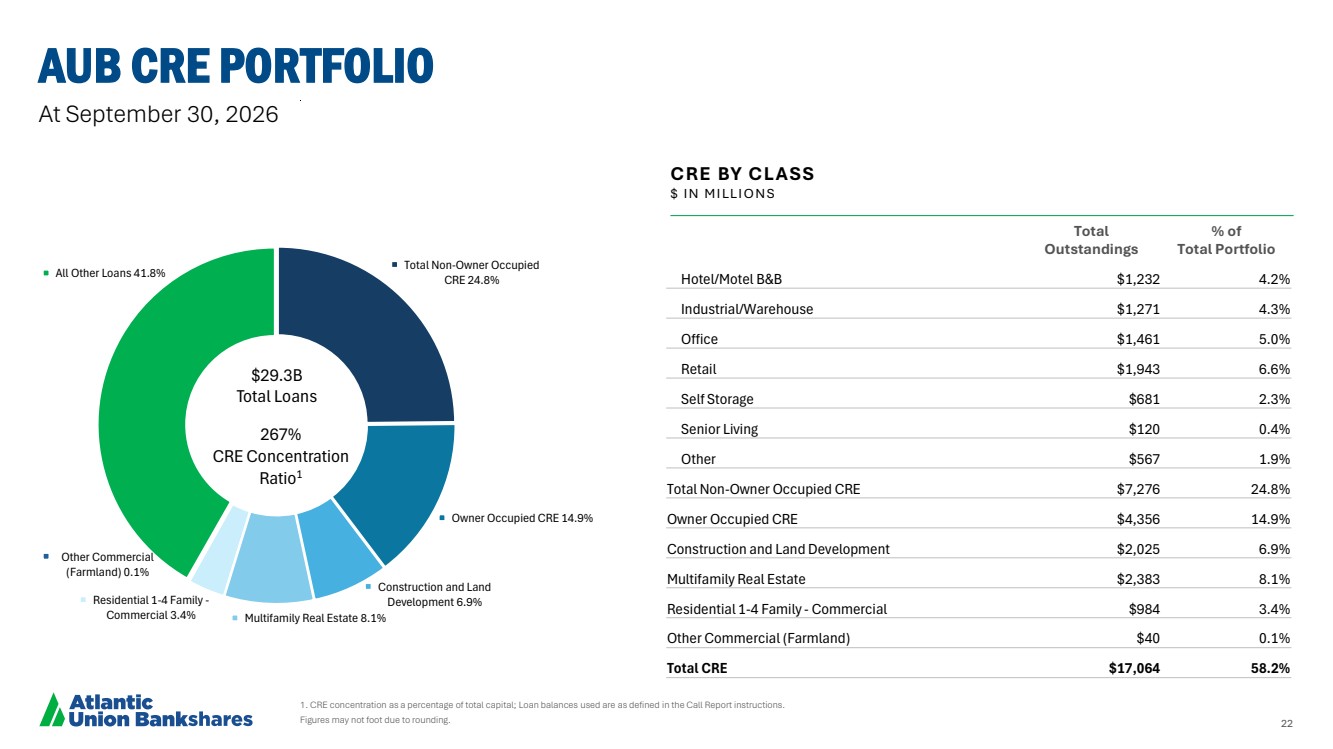
| 22 Total Non-Owner Occupied CRE 24.8% Owner Occupied CRE 14.9% Construction and Land Development 6.9% Multifamily Real Estate 8.1% Residential 1-4 Family - Commercial 3.4% Other Commercial (Farmland) 0.1% All Other Loans 41.8% AUB CRE PORTFOLIO At September 30, 2026 CRE BY CLASS $ I N M I LLI O N S Total Outstandings % of Total Portfolio Hotel/Motel B&B $1,232 4.2% Industrial/Warehouse $1,271 4.3% Office $1,461 5.0% Retail $1,943 6.6% Self Storage $681 2.3% Senior Living $120 0.4% Other $567 1.9% Total Non-Owner Occupied CRE $7,276 24.8% Owner Occupied CRE $4,356 14.9% Construction and Land Development $2,025 6.9% Multifamily Real Estate $2,383 8.1% Residential 1-4 Family - Commercial $984 3.4% Other Commercial (Farmland) $40 0.1% Total CRE $17,064 58.2% $29.3B Total Loans 267% CRE Concentration Ratio1 1. CRE concentration as a percentage of total capital; Loan balances used are as defined in the Call Report instructions. Figures may not foot due to rounding. |
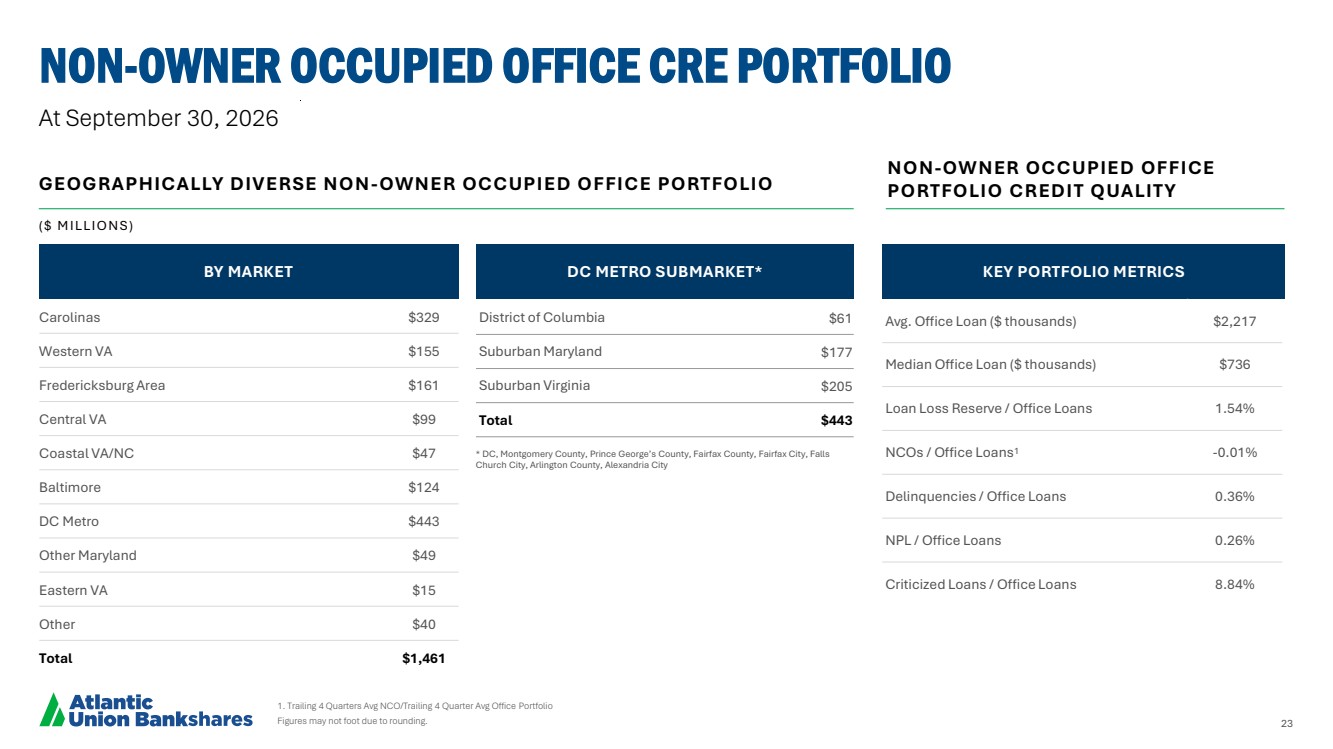
| 23 At September 30, 2026 1. Trailing 4 Quarters Avg NCO/Trailing 4 Quarter Avg Office Portfolio Figures may not foot due to rounding. NON-OWNER OCCUPIED OFFICE CRE PORTFOLIO NON-OWNER OCCUPIED OFFICE GEOGRAPHICALLY DIVERSE NON PORTFOLIO CREDIT QUALITY -OWNER OCCUPIED OFFICE PORTFOLIO * DC, Montgomery County, Prince George’s County, Fairfax County, Fairfax City, Falls Church City, Arlington County, Alexandria City ( $ M I LLI O N S ) Carolinas $329 Western VA $155 Fredericksburg Area $161 Central VA $99 Coastal VA/NC $47 Baltimore $124 DC Metro $443 Other Maryland $49 Eastern VA $15 Other $40 Total $1,461 BY MARKET DC METRO SUBMARKET* KEY PORTFOLIO METRICS Avg. Office Loan ($ thousands) $2,217 Median Office Loan ($ thousands) $736 Loan Loss Reserve / Office Loans 1.54% NCOs / Office Loans1 -0.01% Delinquencies / Office Loans 0.36% NPL / Office Loans 0.26% Criticized Loans / Office Loans 8.84% District of Columbia $61 Suburban Maryland $177 Suburban Virginia $205 Total $443 |
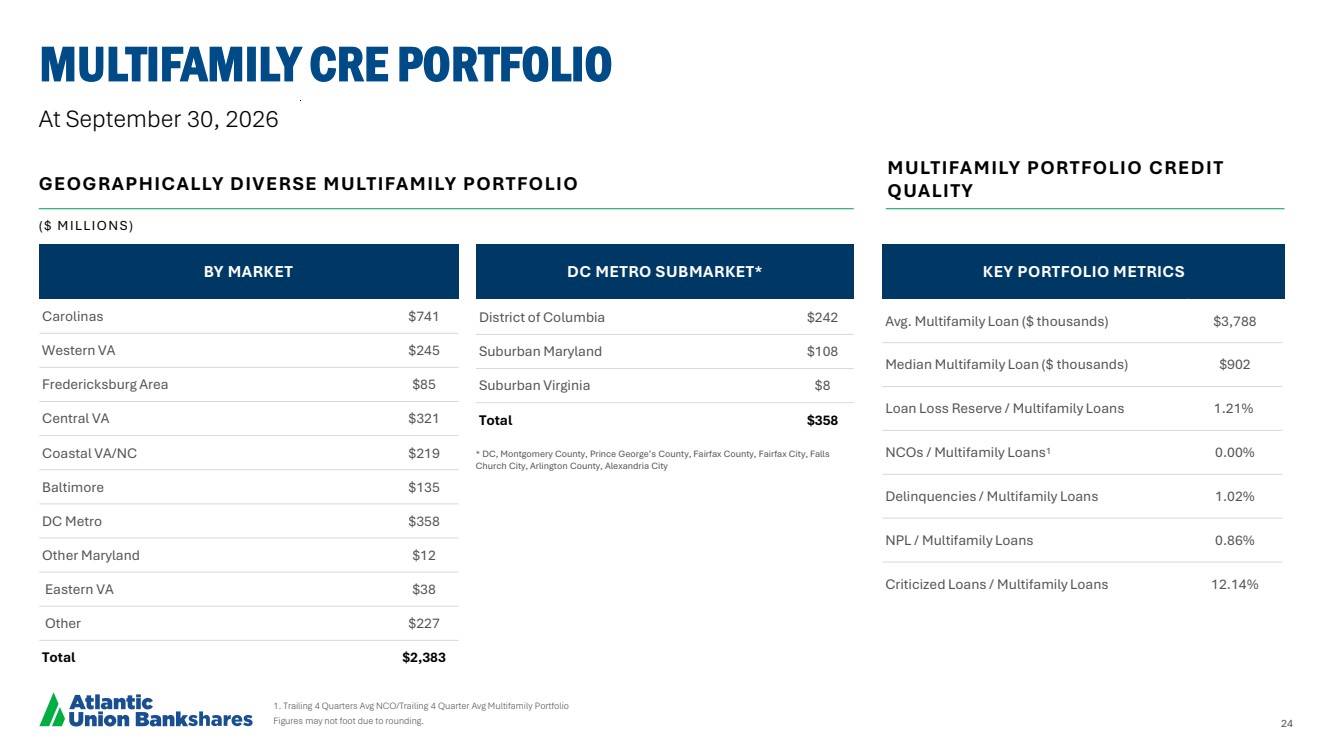
| 24 MULTIFAMILY CRE PORTFOLIO 1. Trailing 4 Quarters Avg NCO/Trailing 4 Quarter Avg Multifamily Portfolio Figures may not foot due to rounding. Carolinas $741 Western VA $245 Fredericksburg Area $85 Central VA $321 Coastal VA/NC $219 Baltimore $135 DC Metro $358 Other Maryland $12 Eastern VA $38 Other $227 Total $2,383 At September 30, 2026 * DC, Montgomery County, Prince George’s County, Fairfax County, Fairfax City, Falls Church City, Arlington County, Alexandria City BY MARKET MULTIFAMILY PORTFOLIO CREDIT GEOGRAPHICALLY DIVERSE MULTIFAMILY PORTFOLIO QUALITY DC METRO SUBMARKET* KEY PORTFOLIO METRICS ( $ M I LLI O N S ) Avg. Multifamily Loan ($ thousands) $3,788 Median Multifamily Loan ($ thousands) $902 Loan Loss Reserve / Multifamily Loans 1.21% NCOs / Multifamily Loans1 0.00% Delinquencies / Multifamily Loans 1.02% NPL / Multifamily Loans 0.86% Criticized Loans / Multifamily Loans 12.14% District of Columbia $242 Suburban Maryland $108 Suburban Virginia $8 Total $358 |
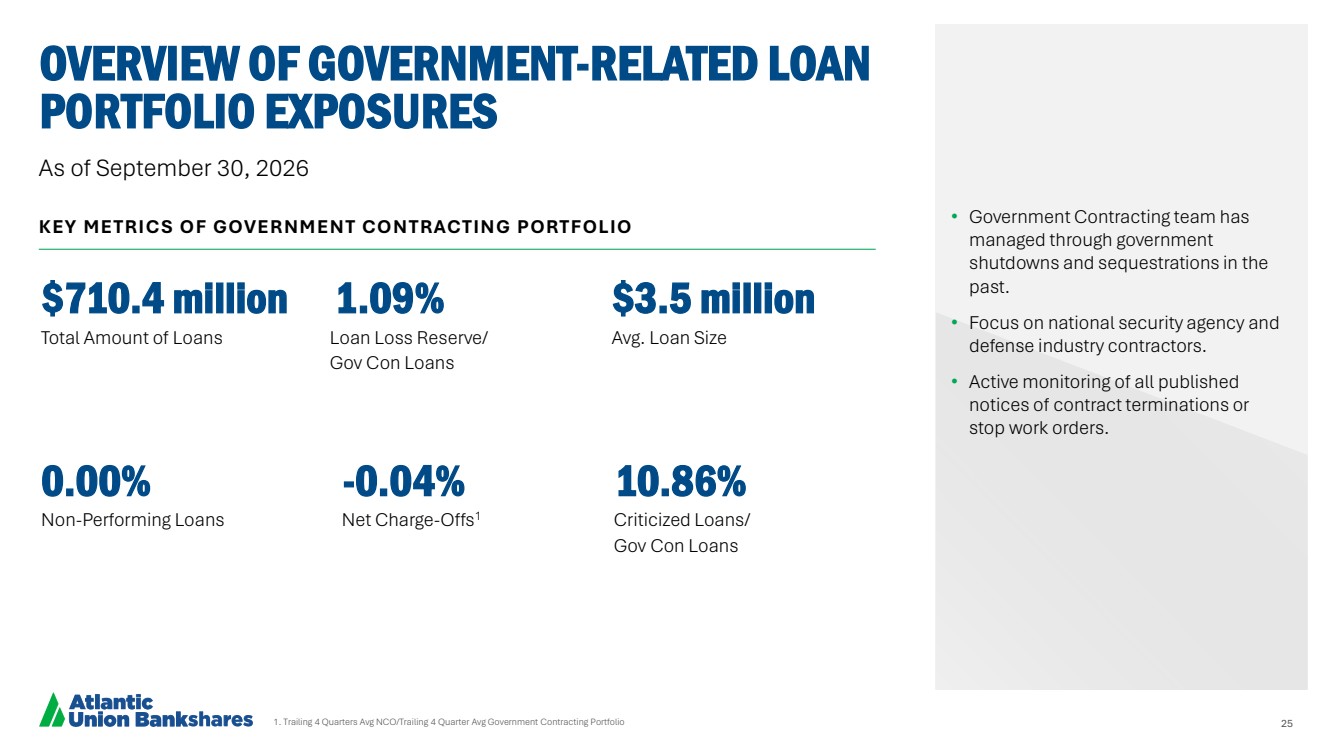
| 25 OVERVIEW OF GOVERNMENT-RELATED LOAN PORTFOLIO EXPOSURES $710.4 million 1.09% $3.5 million Total Amount of Loans Loan Loss Reserve/ Gov Con Loans Avg. Loan Size 0.00% -0.04% 10.86% Non-Performing Loans Net Charge-Offs1 Criticized Loans/ Gov Con Loans 1. Trailing 4 Quarters Avg NCO/Trailing 4 Quarter Avg Government Contracting Portfolio • Government Contracting team has managed through government shutdowns and sequestrations in the past. • Focus on national security agency and defense industry contractors. • Active monitoring of all published notices of contract terminations or stop work orders. KEY METRICS OF GOVERNMENT CONTRACTING PORTFOLIO As of September 30, 2026 |
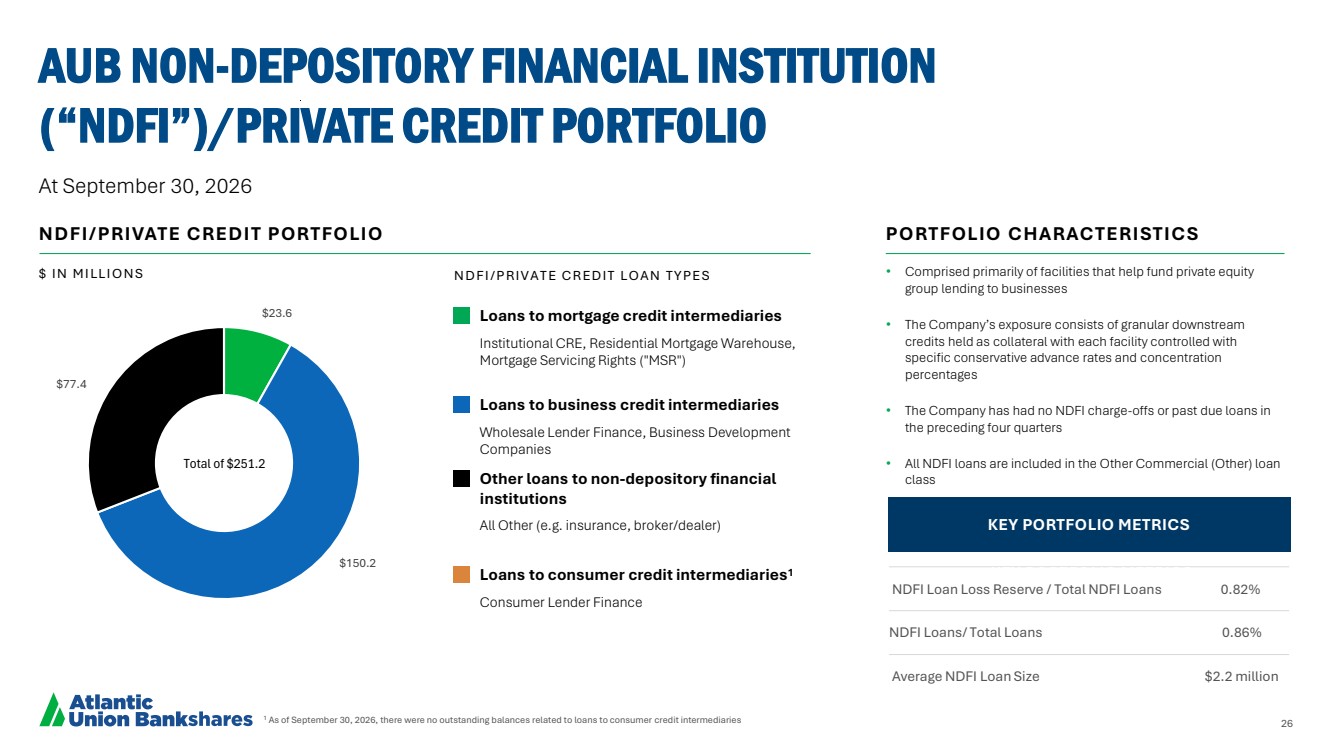
| 26 • Comprised primarily of facilities that help fund private equity group lending to businesses • The Company’s exposure consists of granular downstream credits held as collateral with each facility controlled with specific conservative advance rates and concentration percentages • The Company has had no NDFI charge-offs or past due loans in the preceding four quarters • All NDFI loans are included in the Other Commercial (Other) loan class 1 As of September 30, 2026, there were no outstanding balances related to loans to consumer credit intermediaries AUB NON-DEPOSITORY FINANCIAL INSTITUTION (“NDFI”)/PRIVATE CREDIT PORTFOLIO At September 30, 2026 NDFI/PRIVATE CREDIT PORTFOLIO PORTFOLIO CHARACTERISTICS $ I N M I LLI O N S Loans to mortgage credit intermediaries Institutional CRE, Residential Mortgage Warehouse, Mortgage Servicing Rights ("MSR") Loans to business credit intermediaries Wholesale Lender Finance, Business Development Companies Other loans to non-depository financial institutions All Other (e.g. insurance, broker/dealer) Loans to consumer credit intermediaries1 Consumer Lender Finance N D F I / P R I V A T E C R E D I T LO A N T Y P E S Total of $251.2 NDFI Loan Loss Reserve / Total NDFI Loans 0.82% NDFI Loans/ Total Loans 0.86% Average NDFI Loan Size $2.2 million KEY PORTFOLIO METRICS KEY PORTFOLIO METRICS $23.6 $150.2 $77.4 |
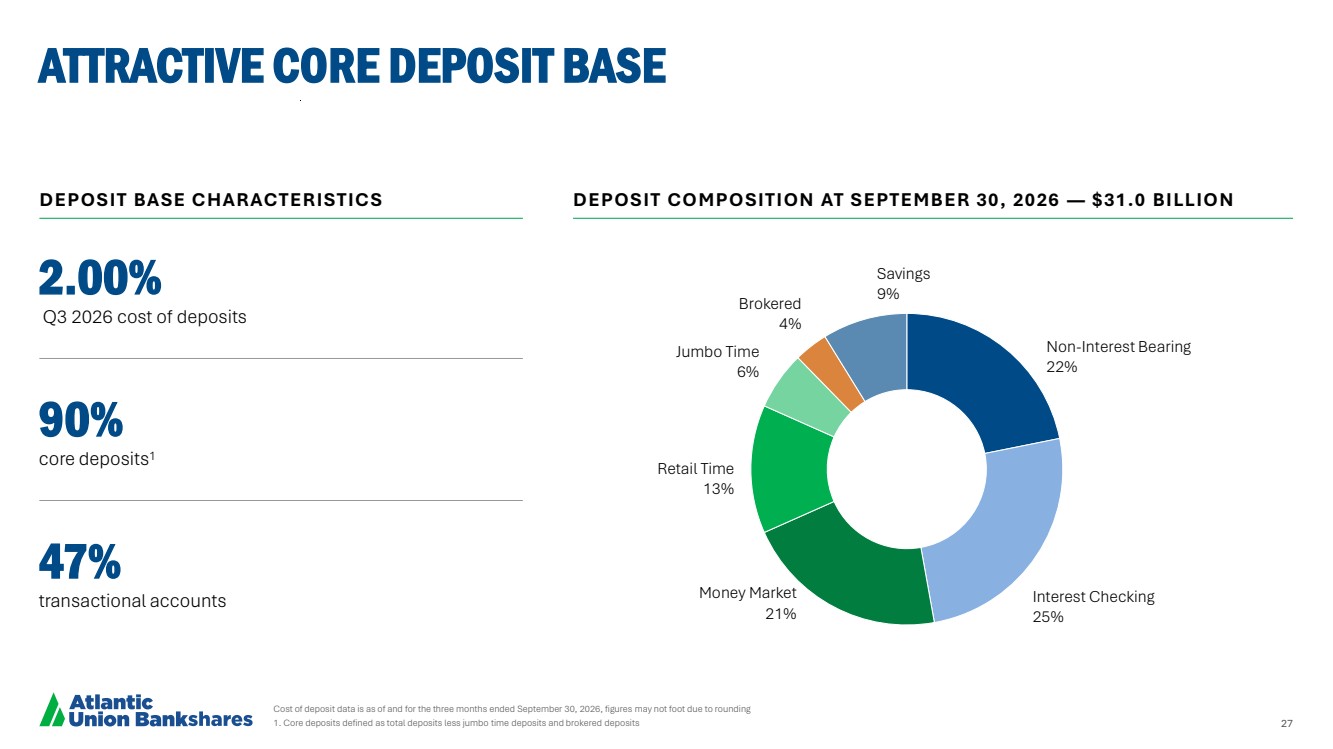
| 27 ATTRACTIVE CORE DEPOSIT BASE Cost of deposit data is as of and for the three months ended September 30, 2026, figures may not foot due to rounding 1. Core deposits defined as total deposits less jumbo time deposits and brokered deposits Non-Interest Bearing 22% Interest Checking 25% Money Market 21% Retail Time 13% Jumbo Time 6% Brokered 4% Savings 9% DEPOSIT BASE CHARACTERISTICS DEPOSIT COMPOSITION AT SEPTEMBER 30, 2026 — $31.0 BILLION 90% core deposits1 47% transactional accounts 2.00% Q3 2026 cost of deposits |
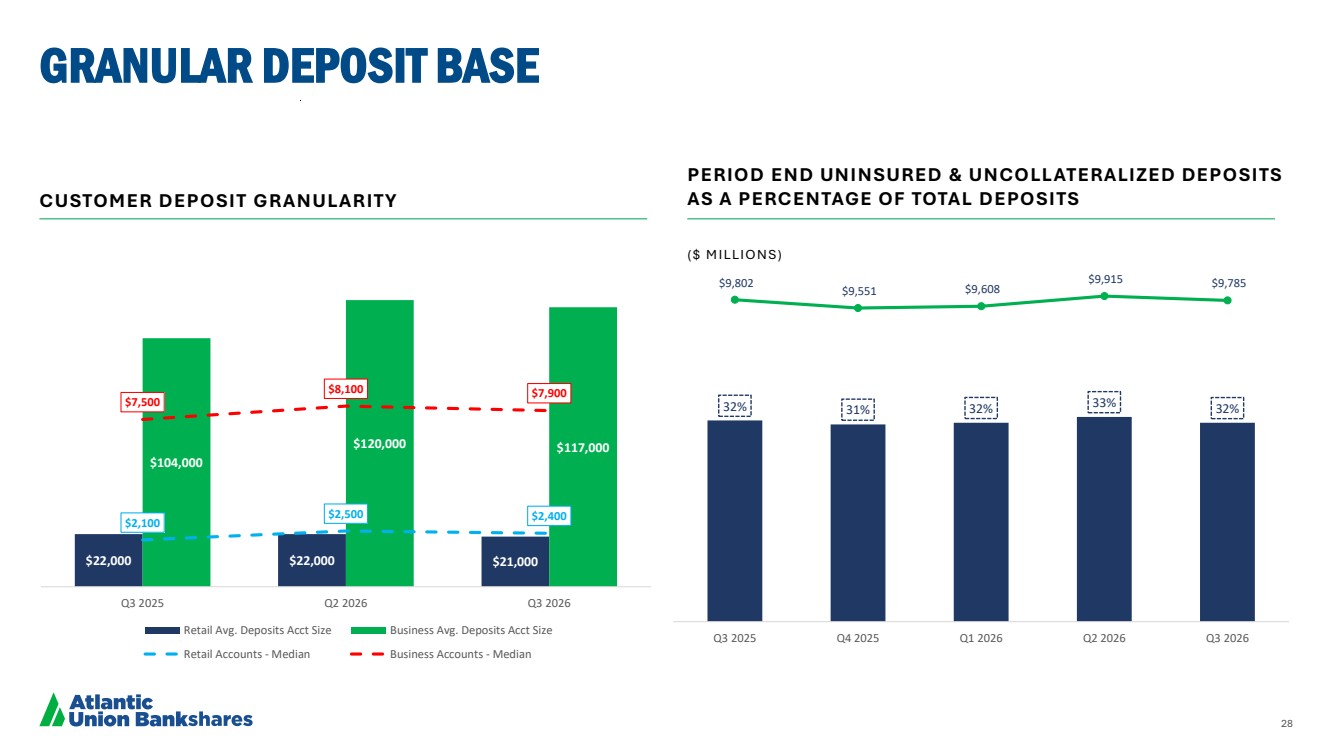
| 28 GRANULAR DEPOSIT BASE CUSTOMER DEPOSIT GRANULARITY PERIOD END UNINSURED & UNCOLLATERALIZED DEPOSITS AS A PERCENTAGE OF TOTAL DEPOSITS ( $ M I LLI O N S ) 32% 31% 32% 33% 32% $9,802 $9,551 $9,608 $9,915 $9,785 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2026 $22,000 $22,000 $21,000 $104,000 $120,000 $117,000 $2,100 $2,500 $2,400 $7,500 $8,100 $7,900 Q3 2025 Q2 2026 Q3 2026 Retail Avg. Deposits Acct Size Business Avg. Deposits Acct Size Retail Accounts - Median Business Accounts - Median |
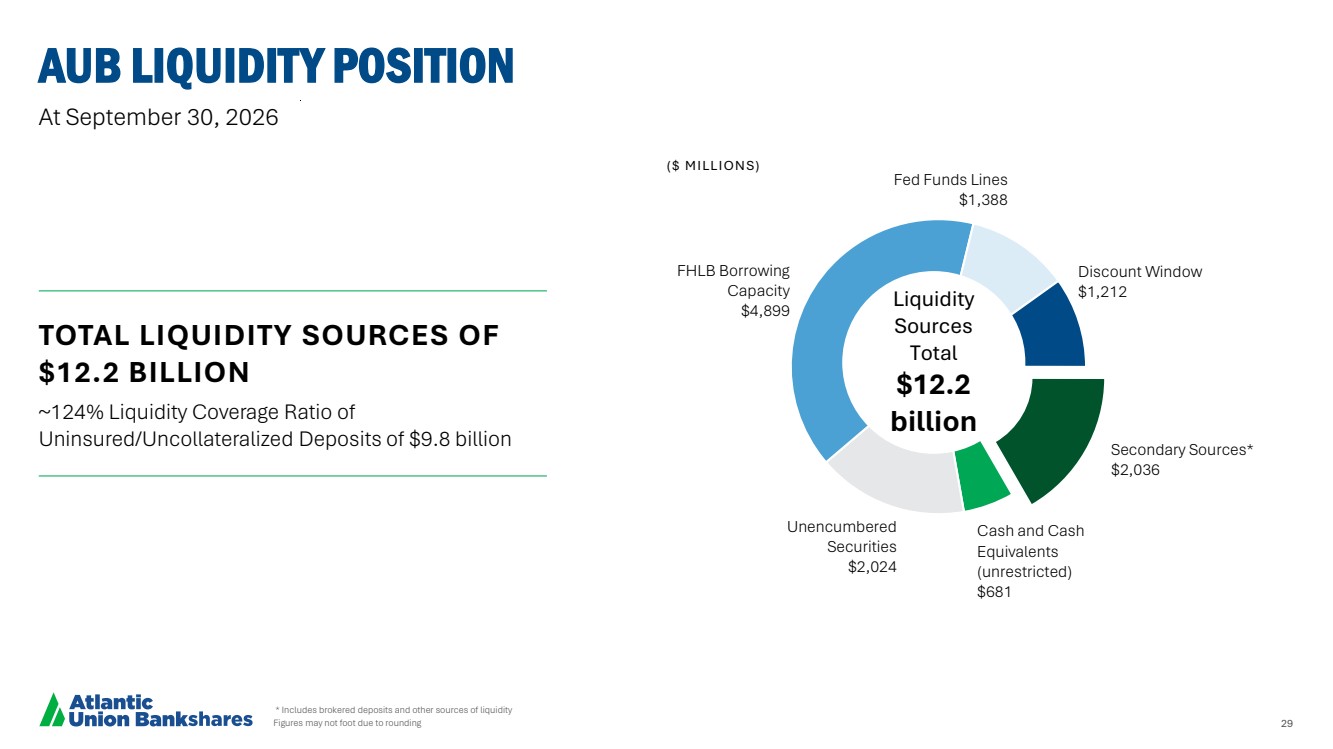
| 29 Cash and Cash Equivalents (unrestricted) $681 Unencumbered Securities $2,024 FHLB Borrowing Capacity $4,899 Fed Funds Lines $1,388 Discount Window $1,212 Secondary Sources* $2,036 AUB LIQUIDITY POSITION * Includes brokered deposits and other sources of liquidity Figures may not foot due to rounding Liquidity Sources Total $12.2 billion At September 30, 2026 TOTAL LIQUIDITY SOURCES OF $12.2 BILLION ~124% Liquidity Coverage Ratio of Uninsured/Uncollateralized Deposits of $9.8 billion ($ MILLIONS) |
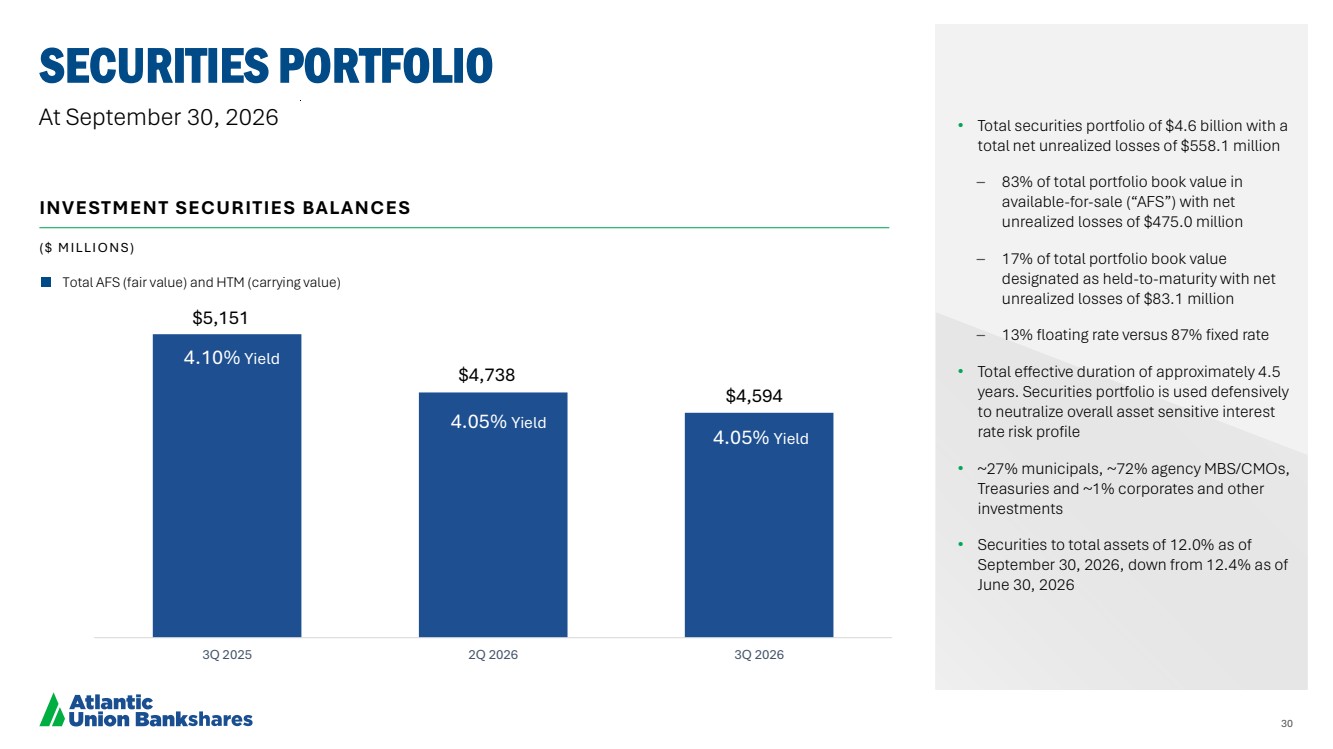
| 30 SECURITIES PORTFOLIO • Total securities portfolio of $4.6 billion with a total net unrealized losses of $558.1 million – 83% of total portfolio book value in available-for-sale (“AFS”) with net unrealized losses of $475.0 million – 17% of total portfolio book value designated as held-to-maturity with net unrealized losses of $83.1 million – 13% floating rate versus 87% fixed rate • Total effective duration of approximately 4.5 years. Securities portfolio is used defensively to neutralize overall asset sensitive interest rate risk profile • ~27% municipals, ~72% agency MBS/CMOs, Treasuries and ~1% corporates and other investments • Securities to total assets of 12.0% as of September 30, 2026, down from 12.4% as of June 30, 2026 $5,151 $4,738 $4,594 3Q 2025 2Q 2026 3Q 2026 4.10% Yield 4.05% Yield 4.05% Yield INVESTMENT SECURITIES BALANCES Total AFS (fair value) and HTM (carrying value) At September 30, 2026 ( $ M I L L I O N S ) |
| 31 RECONCILIATION OF NON-GAAP DISCLOSURES We have provided supplemental performance measures determined by methods other than in accordance with GAAP. These non-GAAP financial measures are a supplement to GAAP, which we use to prepare our financial statements, and should not be considered in isolation or as a substitute for comparable measures calculated in accordance with GAAP. In addition, our non-GAAP financial measures may not be comparable to non-GAAP financial measures of other companies. We use the non-GAAP financial measures discussed herein in our analysis of our performance. Management believes that these non-GAAP financial measures provide additional understanding of ongoing operations, enhance the comparability of our results of operations with prior periods and show the effects of significant gains and charges in the periods presented without the impact of items or events that may obscure trends in our underlying performance or show the potential effects of accumulated other comprehensive income or unrealized losses on held to maturity securities on our capital. Due to the impact of completing the Sandy Spring acquisition in the second quarter of 2025 and the acquisition of American National Bankshares in the second quarter of 2024, we updated our non-GAAP operating measures beginning in the second quarter of 2025 to exclude the CECL Day 1 non-PCD loans and RUC provision expense. The CECL Day 1 non-PCD loans and RUC provision expense is comprised of the initial provision expense on non-PCD loans, which represents the CECL “double count” of the non-PCD credit mark, and the additional provision for unfunded commitments. The Company does not view the CECL Day 1 non-PCD loans and RUC provision expense as organic costs to run the Company’s business and believes this updated presentation provides investors with additional information to assist in period-to-period and company-to-company comparisons of operating performance, which will aid investors in analyzing the Company’s performance. Prior period non-GAAP operating measures presented in this presentation have been recast to conform to this updated presentation. |
| 32 RECONCILIATION OF NON-GAAP DISCLOSURES Adjusted operating measures exclude or include, as applicable, loss on debt extinguishment, gain on sale of equity interest in Bearing Insurance, and gain on sale of securities. The Company believes these non-GAAP adjusted measures provide investors with important information about the continuing economic results of the Company’s operations. The Company believes net interest income (FTE), total revenue (FTE), and total adjusted revenue (FTE), which are used in computing net interest margin (FTE), efficiency ratio (FTE) and adjusted operating efficiency ratio (FTE), provide valuable additional insight into the net interest margin and the efficiency ratio by adjusting for differences in tax treatment of interest income sources. The entire FTE adjustment is attributable to interest income on earning assets, which is used in computing the yield on earning assets. Interest expense and the related cost of interest-bearing liabilities and cost of funds ratios are not affected by the FTE components. The adjusted operating efficiency ratio (FTE) excludes, as applicable, the loss on debt extinguishment, amortization of intangible assets, gain on sale of securities, and gain on sale of equity interest in Bearing Insurance. This measure is similar to the measure used by the Company when analyzing corporate performance and is also similar to the measure used for incentive compensation. The Company believes this adjusted measure provides investors with important information about the continuing economic results of the Company’s operations. ADJUSTED OPERATING EARNINGS AND EFFICIENCY RATIO (Dollars in thousands, except per share amounts) For the three months ended September 30, 2026 June 30, 2026 Operating Measures Net Income (GAAP) $ 136,632 $ 161,013 Plus: Loss on debt extinguishment, net of tax 1,977 — Less: Gain on sale of equity interest in Bearing Insurance, net of tax — 24,023 Less: Gain on sale of securities, net of tax 8 3 Adjusted operating earnings (non-GAAP) $ 138,601 $ 136,987 Less: Dividends on preferred stock 2,967 2,967 Adjusted operating earnings available to common shareholders (non-GAAP) $ 135,634 $ 134,020 Weighted average common shares outstanding, diluted 141,641,618 142,320,806 EPS available to common shareholders, diluted (GAAP) $ 0.94 $ 1.11 Adjusted operating EPS available to common shareholders (non-GAAP) $ 0.96 $ 0.94 Operating Efficiency Ratio Noninterest expense (GAAP) $ 204,333 $ 199,136 Less: Loss on debt extinguishment 2,654 — Less: Amortization of intangible assets 14,946 15,136 Adjusted operating noninterest expense (non-GAAP) $ 186,733 $ 184,000 Noninterest income (GAAP) $ 54,792 $ 90,248 Less: Gain on sale of securities 10 4 Less: Gain on sale of equity interest in Bearing Insurance — 32,350 Adjusted operating noninterest income (non-GAAP) $ 54,782 $ 57,894 Net interest income (GAAP) $ 328,422 $ 325,118 Noninterest income (GAAP) 54,792 90,248 Total revenue (GAAP) $ 383,214 $ 415,366 Net interest income (FTE) (non-GAAP) $ 333,115 $ 329,679 Adjusted operating noninterest income (non-GAAP) 54,782 57,894 Total adjusted revenue (FTE) (non-GAAP) $ 387,897 $ 387,573 Efficiency ratio (GAAP) 53.32% 47.94% Efficiency ratio FTE (non-GAAP) 52.68% 47.42% Adjusted operating efficiency ratio (FTE) (non-GAAP) 48.14% 47.47% |
| 33 RECONCILIATION OF NON-GAAP DISCLOSURES Adjusted operating measures exclude or include, as applicable, merger-related costs, FDIC special assessments, legal reserves associated with our previously disclosed settlement with the Consumer Financial Protection Bureau (“CFPB”), strategic cost savings initiatives (principally composed of severance charges related to headcount reductions, costs related to modifying certain third party vendor contracts, and charges for exiting certain leases), strategic branch closing and related facility consolidation costs (principally composed of real estate, leases and other asset write downs, as well as severance and expense reduction initiatives), the net loss related to balance sheet repositioning (principally composed of gains and losses on debt extinguishment, and charges for exiting certain leases), deferred tax asset write-down, CECL Day 1 non-Purchased Credit Deteriorated (“PCD”) loans and RUC provision expense, loss on debt extinguishment, gain (loss) on sale of securities, gain on sale-leaseback transaction, gain on CRE loan sale, gain on sale of Dixon, Hubard, Feinour & Brown, Inc. (“DHFB”), gain on sale of equity interest in Cary Street Partners (“CSP”), gain on sale of equity interest in Bearing Insurance, and gain on the sale of Visa, Inc. Class B common stock. The Company believes these non-GAAP adjusted measures provide investors with important information about the continuing economic results of the Company’s operations. ADJUSTED OPERATING EARNINGS & FINANCIAL METRICS For the nine months ended For the years ended (Dollars in thousands, except outstanding share and per share amounts) September 30, 2026 2025 2024 2023 2022 2021 Operating Measures Net Income (GAAP) $ 419,811 $ 273,715 $ 209,131 $ 201,818 $ 234,510 $ 263,917 Plus: Merger-related costs, net of tax 6,956 124,590 33,476 2,850 — — Plus: FDIC special assessment, net of tax — — 664 2,656 — — Plus: Legal reserve, net of tax — — — 6,809 — — Plus: Strategic cost saving initiatives, net of tax — — — 9,959 — — Plus: Strategic branch closing and facility consolidation costs, net of tax — — — — 4,351 13,775 Plus: Net loss related to balance sheet repositioning, net of tax — — — — — 11,609 Plus: Deferred tax asset write-down — — 4,774 — — — Plus: CECL Day 1 non-PCD loans and RUC provision expense, net of tax — 77,742 11,520 — — — Plus: Loss on debt extinguishment, net of tax 1,977 — — — — — Less: Gain (loss) on sale of securities, net of tax 12 (62) (5,129) (32,381) (2) 69 Less: Gain on sale-leaseback transaction, net of tax — — — 23,367 — — Less: Gain on CRE loan sale, net of tax — 8,405 — — — — Less: Gain on sale of DHFB, net of tax — — — — 7,984 — Less: Gain on sale of equity interest in CSP, net of tax — 10,994 — — — — Less: Gain on sale of equity interest in Bearing Insurance, net of tax 24,023 — — — — — Less: Gain on Visa, Inc. Class B common stock, net of tax — — — — — 4,058 Adjusted operating earnings (non-GAAP) $ 404,709 $ 456,710 $ 264,694 $ 233,106 $ 230,879 $ 285,174 Less: Dividends on preferred stock 8,901 11,868 11,868 11,868 11,868 11,868 Adjusted operating earnings available to common shareholders (non-GAAP) $ 395,808 $ 444,842 $ 252,826 $ 221,238 $ 219,011 $ 273,306 Earnings per share (EPS) Weighted average common shares outstanding, diluted 142,078,792 129,161,421 87,909,237 74,962,363 74,953,398 77,417,801 EPS available to common shareholders, diluted (GAAP) $ 2.89 $ 2.03 $ 2.24 $ 2.53 $ 2.97 $ 3.26 Adjusted operating EPS available to common shareholders, diluted (non-GAAP) $ 2.79 $ 3.44 $ 2.88 $ 2.95 $ 2.92 $ 3.53 |
| 34 RECONCILIATION OF NON-GAAP DISCLOSURES The Company believes net interest income (FTE), total revenue (FTE), and total adjusted revenue (FTE), which are used in computing net interest margin (FTE) and adjusted operating efficiency ratio (FTE), provide valuable additional insight into the net interest margin and the efficiency ratio by adjusting for differences in tax treatment of interest income sources. The entire FTE adjustment is attributable to interest income on earning assets, which is used in computing the yield on earning assets. Interest expense and the related cost of interest-bearing liabilities and cost of funds ratios are not affected by the FTE components. The adjusted operating efficiency ratio (FTE) excludes, as applicable, the amortization of intangible assets, loss on debt extinguishment, losses related to balance sheet repositioning (principally composed of gains and losses on debt extinguishment), merger-related costs, FDIC special assessments, strategic cost savings initiatives (principally composed of severance charges related to headcount reductions, costs related to modifying certain third party vendor contracts, and charges for exiting certain leases), legal reserves associated with our previously disclosed settlement with the CFPB, strategic branch closing and facility consolidation costs (principally composed of real estate, leases and other asset write downs, as well as severance and expense reduction initiatives), gain (loss) on sale of securities, gain on sale-leaseback transaction, gain on sale of DHFB, gain on CRE loan sale, gain on sale of equity interest in CSP, gain on sale of equity interest in Bearing Insurance, and gain on sale of Visa, Inc. Class B common stock. This measure is similar to the measure used by the Company when analyzing corporate performance and is also similar to the measure used for incentive compensation. The Company believes this adjusted measure provides investors with important information about the continuing economic results of the Company’s operations. ADJUSTED OPERATING EARNINGS & EFFICIENCY RATIO For the nine months ended For the years ended (Dollars in thousands) September 30, 2026 2025 2024 2023 2022 2021 Operating Efficiency Ratio Noninterest expense (GAAP) $ 613,279 $ 895,570 $ 507,534 $ 430,371 $ 403,802 $ 419,195 Less: Amortization of intangible assets 45,528 59,668 19,307 8,781 10,815 13,904 Less: Loss on debt extinguishment 2,654 — — — — — Less: Losses related to balance sheet repositioning — — — — — 14,695 Less: Merger-related costs 9,034 157,278 40,018 2,995 — — Less: FDIC special assessment — — 840 3,362 — — Less: Strategic cost saving initiatives — — — 12,607 — — Less: Legal reserve — — — 8,300 — — Less: Strategic branch closing and facility consolidation costs — — — — 5,508 17,437 Adjusted operating noninterest expense (non-GAAP) $ 556,063 $ 678,624 $ 447,369 $ 394,326 $ 387,479 $ 373,159 Noninterest income (GAAP) $ 199,823 $ 219,436 $ 118,878 $ 90,877 $ 118,523 $ 125,806 Less: Gain (loss) on sale of securities 16 (81) (6,493) (40,989) (3) 87 Less: Gain on sale-leaseback transaction — — — 29,579 — — Less: Gain on sale of DHFB — — — — 9,082 — Less: Gain on CRE loan sale — 10,915 — — — — Less: Gain on sale of equity interest in CSP — 14,757 — — — — Less: Gain on sale of equity interest in Bearing Insurance 32,350 — — — — — Less: Gain on Visa, Inc. Class B common stock — — — — — 5,137 Adjusted operating noninterest income (non-GAAP) $ 167,457 $ 193,845 $ 125,371 $ 102,287 $ 109,444 $ 120,582 Net interest income (GAAP) $ 965,913 $ 1,154,913 $ 698,539 $ 611,013 $ 584,261 $ 551,260 Noninterest income (GAAP) 199,823 219,436 118,878 90,877 118,523 125,806 Total revenue (GAAP) $ 1,165,736 $ 1,374,349 $ 817,417 $ 701,890 $ 702,784 $ 677,066 Net interest income (FTE) (non-GAAP) $ 979,719 $ 1,172,074 $ 713,765 $ 625,923 $ 599,134 $ 563,851 Adjusted operating noninterest income (non-GAAP) 167,457 193,845 125,371 102,287 109,444 120,582 Total adjusted revenue (FTE) (non-GAAP) $ 1,147,176 $ 1,365,919 $ 839,136 $ 728,210 $ 708,578 $ 684,433 Efficiency ratio (GAAP) 52.61% 65.16% 62.09% 61.32% 57.46% 61.91% Adjusted operating efficiency ratio (FTE) (non-GAAP) 48.47% 49.68% 53.31% 54.15% 54.68% 54.52% |
| 35 RECONCILIATION OF NON-GAAP DISCLOSURES The Company believes net interest income (FTE), interest income (FTE), investment income (FTE), total revenue (FTE), earning asset income (FTE), total adjusted revenue (FTE), which are used in computing net interest margin (FTE), core net interest margin (FTE), loan yield (FTE), investment yield (FTE), earning asset yield (FTE), efficiency ratio (FTE) and adjusted operating efficiency ratio (FTE), provide valuable additional insight into the net interest margin, loan yield, investment yield, earning asset yield, and the efficiency ratio by adjusting for differences in tax treatment of interest income sources. The entire FTE adjustment is attributable to interest income on earning assets, which is used in computing the yield on earning assets. Interest expense and the related cost of interest-bearing liabilities and cost of funds ratios are not affected by the FTE components. NET INTEREST MARGIN, LOAN YIELD, INVESTMENT YIELD AND EARNING ASSET YIELD (Dollars in thousands) For the three months ended September 30, 2026 June 30, 2026 Net interest income (GAAP) $ 328,422 $ 325,118 FTE adjustment 4,693 4,561 Net interest income (FTE) (non-GAAP) $ 333,115 $ 329,679 Noninterest income (GAAP) 54,792 90,248 Total revenue (FTE) (non-GAAP) $ 387,907 $ 419,927 Net interest income (FTE) (non-GAAP) $ 333,115 $ 329,679 Purchase accounting adjustments 40,865 39,939 Core net interest income (FTE) (non-GAAP) $ 292,250 $ 289,740 Average earning assets $ 34,091,046 $ 33,544,840 Net interest margin (GAAP) 3.82% 3.89% Net interest margin (FTE) (non-GAAP) 3.88% 3.94% Core net interest margin (FTE) (non-GAAP) 3.40% 3.46% Loan interest income (GAAP) $ 451,275 $ 436,309 FTE adjustment 2,336 2,199 Loan interest income (FTE) (non-GAAP) $ 453,611 $ 438,508 Average LHFI $ 28,927,866 $ 28,243,611 Loan yield (GAAP) 6.19% 6.20% Loan yield (FTE) (non-GAAP) 6.22% 6.23% Investment interest income (GAAP) $ 47,658 $ 47,856 FTE adjustment 2,357 2,362 Investment interest income (FTE) (non-GAAP) $ 50,015 $ 50,218 Average securities $ 4,895,169 $ 4,976,527 Investment yield (GAAP) 3.86% 3.86% Investment yield (FTE) (non-GAAP) 4.05% 4.05% Total earning assets interest income (GAAP) $ 501,133 $ 486,828 FTE adjustment 4,693 4,561 Total earning assets interest income (FTE) (non-GAAP) $ 505,826 $ 491,389 Average earning assets $ 34,091,046 $ 33,544,840 Earning assets yield (GAAP) 5.83% 5.82% Earning assets yield (FTE) (non-GAAP) 5.89% 5.88% |
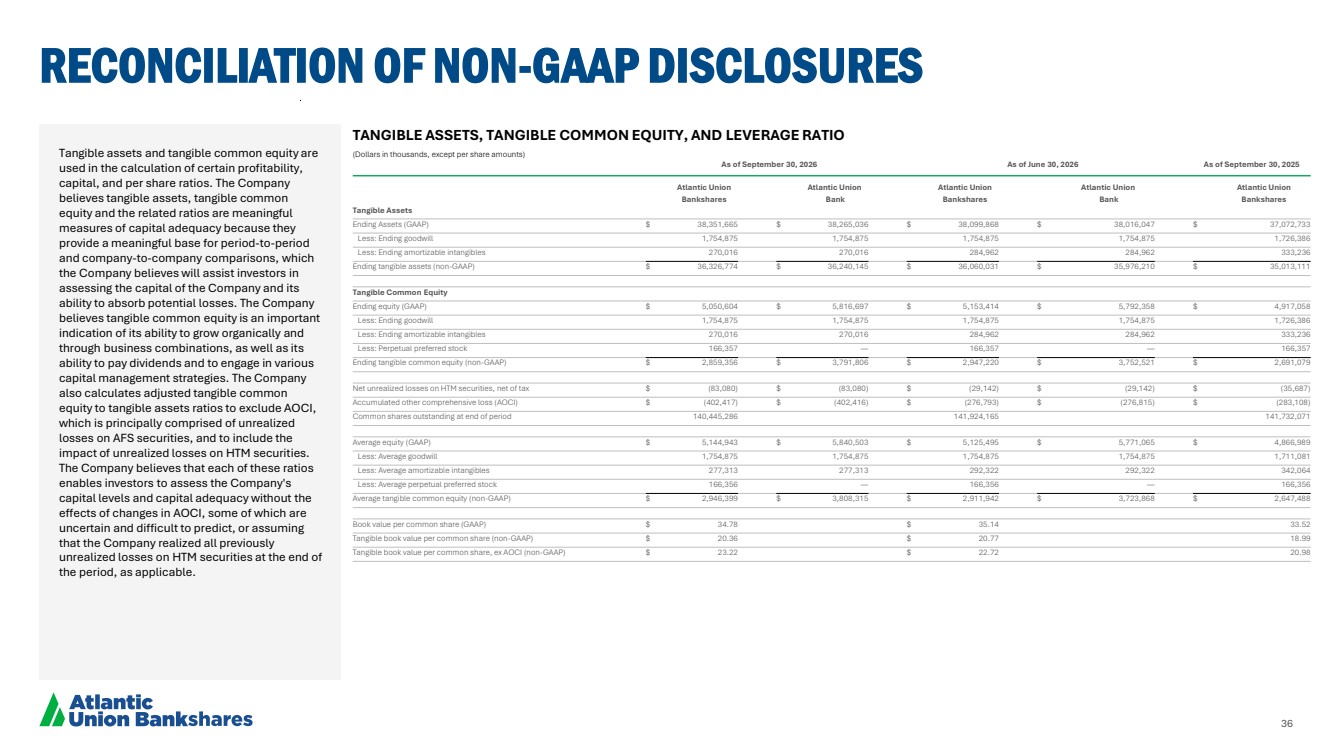
| 36 RECONCILIATION OF NON-GAAP DISCLOSURES Tangible assets and tangible common equity are used in the calculation of certain profitability, capital, and per share ratios. The Company believes tangible assets, tangible common equity and the related ratios are meaningful measures of capital adequacy because they provide a meaningful base for period-to-period and company-to-company comparisons, which the Company believes will assist investors in assessing the capital of the Company and its ability to absorb potential losses. The Company believes tangible common equity is an important indication of its ability to grow organically and through business combinations, as well as its ability to pay dividends and to engage in various capital management strategies. The Company also calculates adjusted tangible common equity to tangible assets ratios to exclude AOCI, which is principally comprised of unrealized losses on AFS securities, and to include the impact of unrealized losses on HTM securities. The Company believes that each of these ratios enables investors to assess the Company's capital levels and capital adequacy without the effects of changes in AOCI, some of which are uncertain and difficult to predict, or assuming that the Company realized all previously unrealized losses on HTM securities at the end of the period, as applicable. TANGIBLE ASSETS, TANGIBLE COMMON EQUITY, AND LEVERAGE RATIO (Dollars in thousands, except per share amounts) As of September 30, 2026 As of June 30, 2026 As of September 30, 2025 Atlantic Union Atlantic Union Atlantic Union Atlantic Union Atlantic Union Bankshares Bank Bankshares Bank Bankshares Tangible Assets Ending Assets (GAAP) $ 38,351,665 $ 38,265,036 $ 38,099,868 $ 38,016,047 $ 37,072,733 Less: Ending goodwill 1,754,875 1,754,875 1,754,875 1,754,875 1,726,386 Less: Ending amortizable intangibles 270,016 270,016 284,962 284,962 333,236 Ending tangible assets (non-GAAP) $ 36,326,774 $ 36,240,145 $ 36,060,031 $ 35,976,210 $ 35,013,111 Tangible Common Equity Ending equity (GAAP) $ 5,050,604 $ 5,816,697 $ 5,153,414 $ 5,792,358 $ 4,917,058 Less: Ending goodwill 1,754,875 1,754,875 1,754,875 1,754,875 1,726,386 Less: Ending amortizable intangibles 270,016 270,016 284,962 284,962 333,236 Less: Perpetual preferred stock 166,357 — 166,357 — 166,357 Ending tangible common equity (non-GAAP) $ 2,859,356 $ 3,791,806 $ 2,947,220 $ 3,752,521 $ 2,691,079 Net unrealized losses on HTM securities, net of tax $ (83,080) $ (83,080) $ (29,142) $ (29,142) $ (35,687) Accumulated other comprehensive loss (AOCI) $ (402,417) $ (402,416) $ (276,793) $ (276,815) $ (283,108) Common shares outstanding at end of period 140,445,286 141,924,165 141,732,071 Average equity (GAAP) $ 5,144,943 $ 5,840,503 $ 5,125,495 $ 5,771,065 $ 4,866,989 Less: Average goodwill 1,754,875 1,754,875 1,754,875 1,754,875 1,711,081 Less: Average amortizable intangibles 277,313 277,313 292,322 292,322 342,064 Less: Average perpetual preferred stock 166,356 — 166,356 — 166,356 Average tangible common equity (non-GAAP) $ 2,946,399 $ 3,808,315 $ 2,911,942 $ 3,723,868 $ 2,647,488 Book value per common share (GAAP) $ 34.78 $ 35.14 33.52 Tangible book value per common share (non-GAAP) $ 20.36 $ 20.77 18.99 Tangible book value per common share, ex AOCI (non-GAAP) $ 23.22 $ 22.72 20.98 |
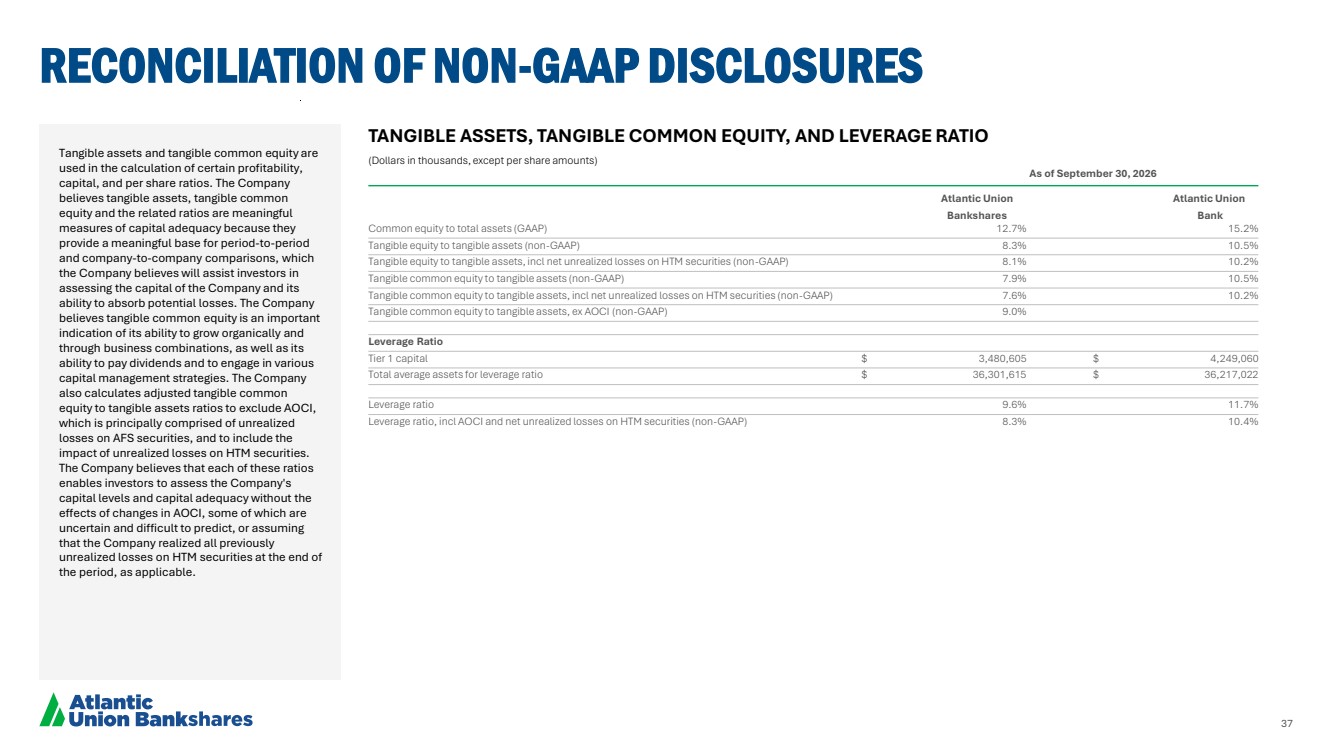
| 37 RECONCILIATION OF NON-GAAP DISCLOSURES Tangible assets and tangible common equity are used in the calculation of certain profitability, capital, and per share ratios. The Company believes tangible assets, tangible common equity and the related ratios are meaningful measures of capital adequacy because they provide a meaningful base for period-to-period and company-to-company comparisons, which the Company believes will assist investors in assessing the capital of the Company and its ability to absorb potential losses. The Company believes tangible common equity is an important indication of its ability to grow organically and through business combinations, as well as its ability to pay dividends and to engage in various capital management strategies. The Company also calculates adjusted tangible common equity to tangible assets ratios to exclude AOCI, which is principally comprised of unrealized losses on AFS securities, and to include the impact of unrealized losses on HTM securities. The Company believes that each of these ratios enables investors to assess the Company's capital levels and capital adequacy without the effects of changes in AOCI, some of which are uncertain and difficult to predict, or assuming that the Company realized all previously unrealized losses on HTM securities at the end of the period, as applicable. TANGIBLE ASSETS, TANGIBLE COMMON EQUITY, AND LEVERAGE RATIO (Dollars in thousands, except per share amounts) As of September 30, 2026 Atlantic Union Atlantic Union Bankshares Bank Common equity to total assets (GAAP) 12.7% 15.2% Tangible equity to tangible assets (non-GAAP) 8.3% 10.5% Tangible equity to tangible assets, incl net unrealized losses on HTM securities (non-GAAP) 8.1% 10.2% Tangible common equity to tangible assets (non-GAAP) 7.9% 10.5% Tangible common equity to tangible assets, incl net unrealized losses on HTM securities (non-GAAP) 7.6% 10.2% Tangible common equity to tangible assets, ex AOCI (non-GAAP) 9.0% Leverage Ratio Tier 1 capital $ 3,480,605 $ 4,249,060 Total average assets for leverage ratio $ 36,301,615 $ 36,217,022 Leverage ratio 9.6% 11.7% Leverage ratio, incl AOCI and net unrealized losses on HTM securities (non-GAAP) 8.3% 10.4% |
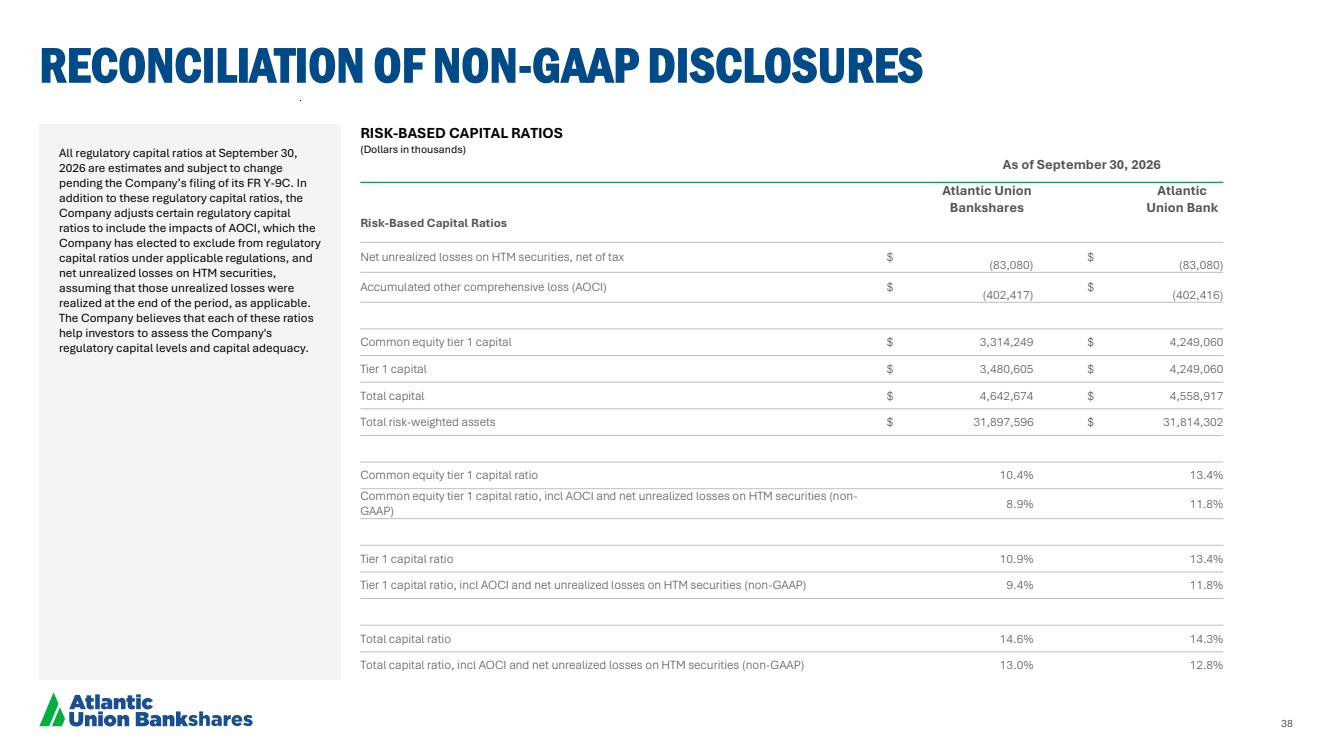
| 38 RECONCILIATION OF NON-GAAP DISCLOSURES All regulatory capital ratios at September 30, 2026 are estimates and subject to change pending the Company’s filing of its FR Y-9C. In addition to these regulatory capital ratios, the Company adjusts certain regulatory capital ratios to include the impacts of AOCI, which the Company has elected to exclude from regulatory capital ratios under applicable regulations, and net unrealized losses on HTM securities, assuming that those unrealized losses were realized at the end of the period, as applicable. The Company believes that each of these ratios help investors to assess the Company's regulatory capital levels and capital adequacy. RISK-BASED CAPITAL RATIOS (Dollars in thousands) As of September 30, 2026 Atlantic Union Bankshares Atlantic Union Bank Risk-Based Capital Ratios Net unrealized losses on HTM securities, net of tax $ (83,080) $ (83,080) Accumulated other comprehensive loss (AOCI) $ (402,417) $ (402,416) Common equity tier 1 capital $ 3,314,249 $ 4,249,060 Tier 1 capital $ 3,480,605 $ 4,249,060 Total capital $ 4,642,674 $ 4,558,917 Total risk-weighted assets $ 31,897,596 $ 31,814,302 Common equity tier 1 capital ratio 10.4% 13.4% Common equity tier 1 capital ratio, incl AOCI and net unrealized losses on HTM securities (non-GAAP) 8.9% 11.8% Tier 1 capital ratio 10.9% 13.4% Tier 1 capital ratio, incl AOCI and net unrealized losses on HTM securities (non-GAAP) 9.4% 11.8% Total capital ratio 14.6% 14.3% Total capital ratio, incl AOCI and net unrealized losses on HTM securities (non-GAAP) 13.0% 12.8% |
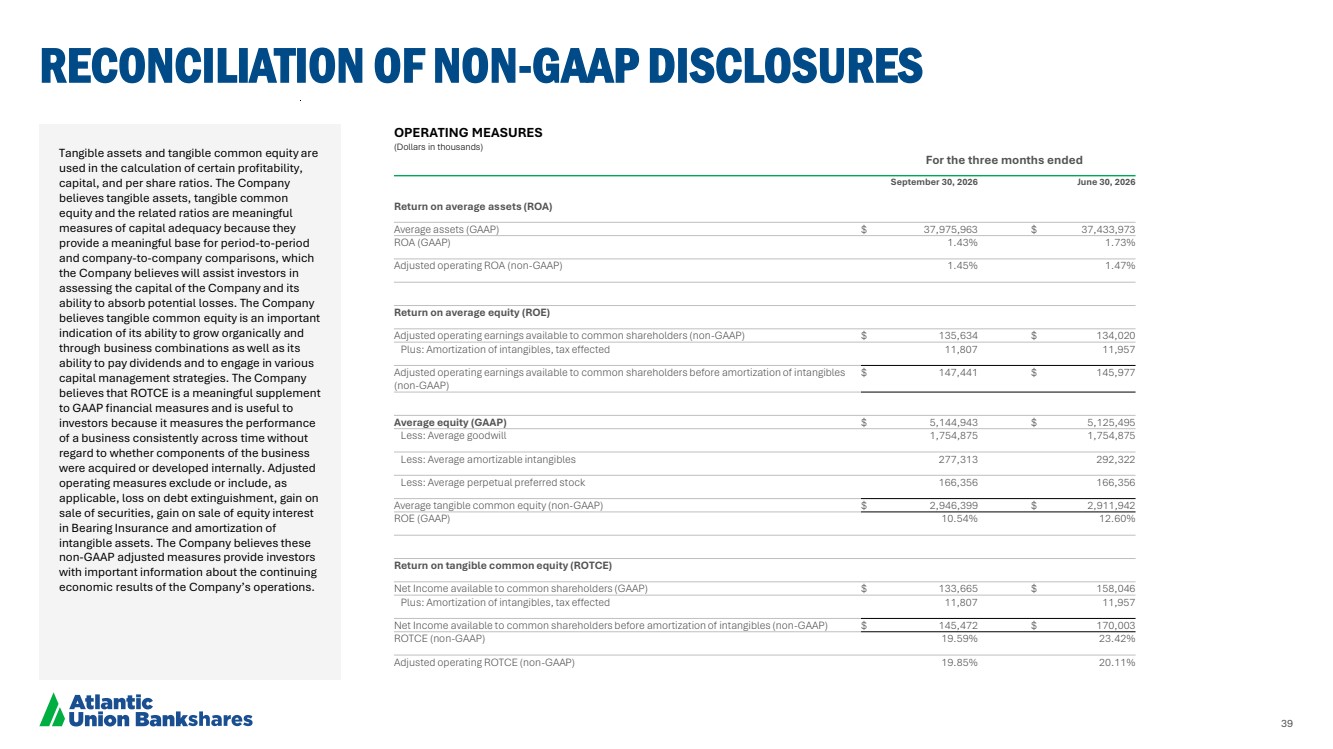
| 39 RECONCILIATION OF NON-GAAP DISCLOSURES Tangible assets and tangible common equity are used in the calculation of certain profitability, capital, and per share ratios. The Company believes tangible assets, tangible common equity and the related ratios are meaningful measures of capital adequacy because they provide a meaningful base for period-to-period and company-to-company comparisons, which the Company believes will assist investors in assessing the capital of the Company and its ability to absorb potential losses. The Company believes tangible common equity is an important indication of its ability to grow organically and through business combinations as well as its ability to pay dividends and to engage in various capital management strategies. The Company believes that ROTCE is a meaningful supplement to GAAP financial measures and is useful to investors because it measures the performance of a business consistently across time without regard to whether components of the business were acquired or developed internally. Adjusted operating measures exclude or include, as applicable, loss on debt extinguishment, gain on sale of securities, gain on sale of equity interest in Bearing Insurance and amortization of intangible assets. The Company believes these non-GAAP adjusted measures provide investors with important information about the continuing economic results of the Company’s operations. OPERATING MEASURES (Dollars in thousands) For the three months ended September 30, 2026 June 30, 2026 Return on average assets (ROA) Average assets (GAAP) $ 37,975,963 $ 37,433,973 ROA (GAAP) 1.43% 1.73% Adjusted operating ROA (non-GAAP) 1.45% 1.47% Return on average equity (ROE) Adjusted operating earnings available to common shareholders (non-GAAP) $ 135,634 $ 134,020 Plus: Amortization of intangibles, tax effected 11,807 11,957 Adjusted operating earnings available to common shareholders before amortization of intangibles (non-GAAP) $ 147,441 $ 145,977 Average equity (GAAP) $ 5,144,943 $ 5,125,495 Less: Average goodwill 1,754,875 1,754,875 Less: Average amortizable intangibles 277,313 292,322 Less: Average perpetual preferred stock 166,356 166,356 Average tangible common equity (non-GAAP) $ 2,946,399 $ 2,911,942 ROE (GAAP) 10.54% 12.60% Return on tangible common equity (ROTCE) Net Income available to common shareholders (GAAP) $ 133,665 $ 158,046 Plus: Amortization of intangibles, tax effected 11,807 11,957 Net Income available to common shareholders before amortization of intangibles (non-GAAP) $ 145,472 $ 170,003 ROTCE (non-GAAP) 19.59% 23.42% Adjusted operating ROTCE (non-GAAP) 19.85% 20.11% |
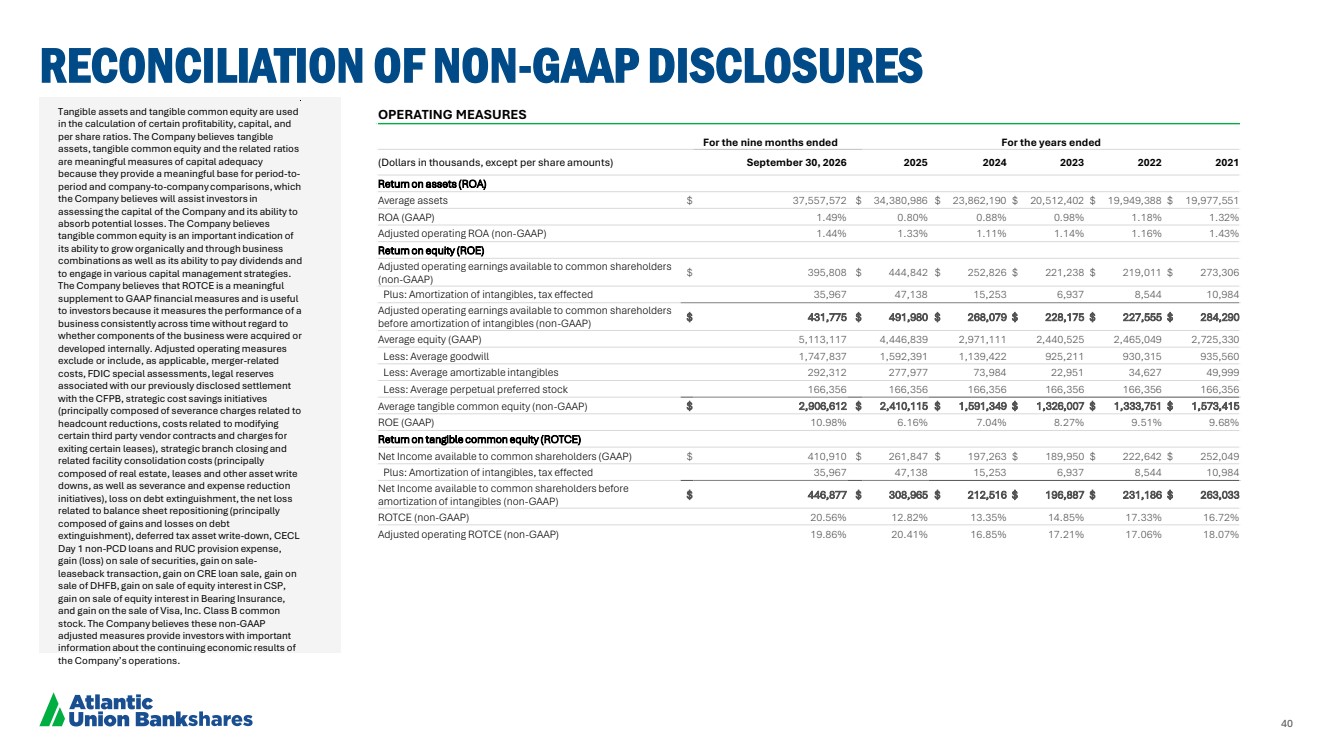
| 40 RECONCILIATION OF NON-GAAP DISCLOSURES Tangible assets and tangible common equity are used in the calculation of certain profitability, capital, and per share ratios. The Company believes tangible assets, tangible common equity and the related ratios are meaningful measures of capital adequacy because they provide a meaningful base for period-to-period and company-to-company comparisons, which the Company believes will assist investors in assessing the capital of the Company and its ability to absorb potential losses. The Company believes tangible common equity is an important indication of its ability to grow organically and through business combinations as well as its ability to pay dividends and to engage in various capital management strategies. The Company believes that ROTCE is a meaningful supplement to GAAP financial measures and is useful to investors because it measures the performance of a business consistently across time without regard to whether components of the business were acquired or developed internally. Adjusted operating measures exclude or include, as applicable, merger-related costs, FDIC special assessments, legal reserves associated with our previously disclosed settlement with the CFPB, strategic cost savings initiatives (principally composed of severance charges related to headcount reductions, costs related to modifying certain third party vendor contracts and charges for exiting certain leases), strategic branch closing and related facility consolidation costs (principally composed of real estate, leases and other asset write downs, as well as severance and expense reduction initiatives), loss on debt extinguishment, the net loss related to balance sheet repositioning (principally composed of gains and losses on debt extinguishment), deferred tax asset write-down, CECL Day 1 non-PCD loans and RUC provision expense, gain (loss) on sale of securities, gain on sale-leaseback transaction, gain on CRE loan sale, gain on sale of DHFB, gain on sale of equity interest in CSP, gain on sale of equity interest in Bearing Insurance, and gain on the sale of Visa, Inc. Class B common stock. The Company believes these non-GAAP adjusted measures provide investors with important information about the continuing economic results of the Company’s operations. OPERATING MEASURES For the nine months ended For the years ended (Dollars in thousands, except per share amounts) September 30, 2026 2025 2024 2023 2022 2021 Return on assets (ROA) Average assets $ 37,557,572 $ 34,380,986 $ 23,862,190 $ 20,512,402 $ 19,949,388 $ 19,977,551 ROA (GAAP) 1.49% 0.80% 0.88% 0.98% 1.18% 1.32% Adjusted operating ROA (non-GAAP) 1.44% 1.33% 1.11% 1.14% 1.16% 1.43% Return on equity (ROE) Adjusted operating earnings available to common shareholders (non-GAAP) $ 395,808 $ 444,842 $ 252,826 $ 221,238 $ 219,011 $ 273,306 Plus: Amortization of intangibles, tax effected 35,967 47,138 15,253 6,937 8,544 10,984 Adjusted operating earnings available to common shareholders before amortization of intangibles (non-GAAP) $ 431,775 $ 491,980 $ 268,079 $ 228,175 $ 227,555 $ 284,290 Average equity (GAAP) 5,113,117 4,446,839 2,971,111 2,440,525 2,465,049 2,725,330 Less: Average goodwill 1,747,837 1,592,391 1,139,422 925,211 930,315 935,560 Less: Average amortizable intangibles 292,312 277,977 73,984 22,951 34,627 49,999 Less: Average perpetual preferred stock 166,356 166,356 166,356 166,356 166,356 166,356 Average tangible common equity (non-GAAP) $ 2,906,612 $ 2,410,115 $ 1,591,349 $ 1,326,007 $ 1,333,751 $ 1,573,415 ROE (GAAP) 10.98% 6.16% 7.04% 8.27% 9.51% 9.68% Return on tangible common equity (ROTCE) Net Income available to common shareholders (GAAP) $ 410,910 $ 261,847 $ 197,263 $ 189,950 $ 222,642 $ 252,049 Plus: Amortization of intangibles, tax effected 35,967 47,138 15,253 6,937 8,544 10,984 Net Income available to common shareholders before amortization of intangibles (non-GAAP) $ 446,877 $ 308,965 $ 212,516 $ 196,887 $ 231,186 $ 263,033 ROTCE (non-GAAP) 20.56% 12.82% 13.35% 14.85% 17.33% 16.72% Adjusted operating ROTCE (non-GAAP) 19.86% 20.41% 16.85% 17.21% 17.06% 18.07% |
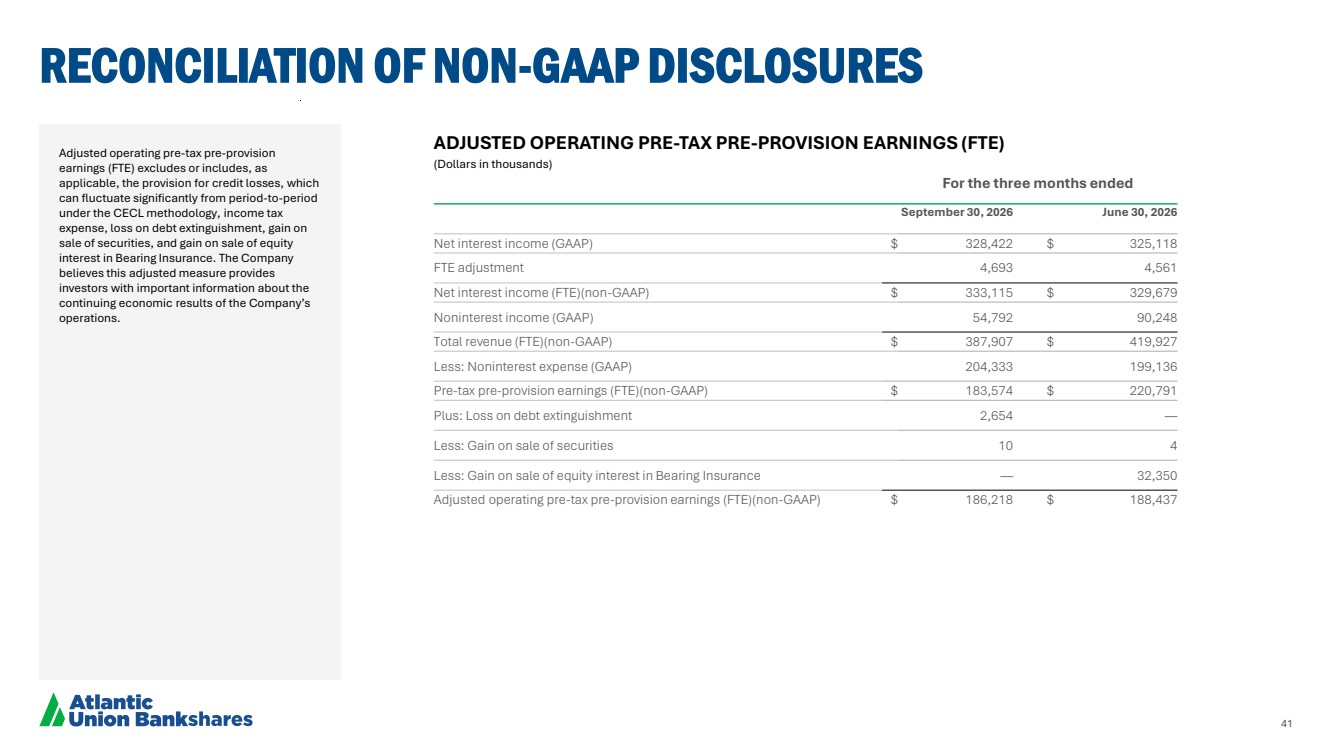
| 41 RECONCILIATION OF NON-GAAP DISCLOSURES Adjusted operating pre-tax pre-provision earnings (FTE) excludes or includes, as applicable, the provision for credit losses, which can fluctuate significantly from period-to-period under the CECL methodology, income tax expense, loss on debt extinguishment, gain on sale of securities, and gain on sale of equity interest in Bearing Insurance. The Company believes this adjusted measure provides investors with important information about the continuing economic results of the Company’s operations. ADJUSTED OPERATING PRE-TAX PRE-PROVISION EARNINGS (FTE) (Dollars in thousands) For the three months ended September 30, 2026 June 30, 2026 Net interest income (GAAP) $ 328,422 $ 325,118 FTE adjustment 4,693 4,561 Net interest income (FTE)(non-GAAP) $ 333,115 $ 329,679 Noninterest income (GAAP) 54,792 90,248 Total revenue (FTE)(non-GAAP) $ 387,907 $ 419,927 Less: Noninterest expense (GAAP) 204,333 199,136 Pre-tax pre-provision earnings (FTE)(non-GAAP) $ 183,574 $ 220,791 Plus: Loss on debt extinguishment 2,654 — Less: Gain on sale of securities 10 4 Less: Gain on sale of equity interest in Bearing Insurance — 32,350 Adjusted operating pre-tax pre-provision earnings (FTE)(non-GAAP) $ 186,218 $ 188,437 |